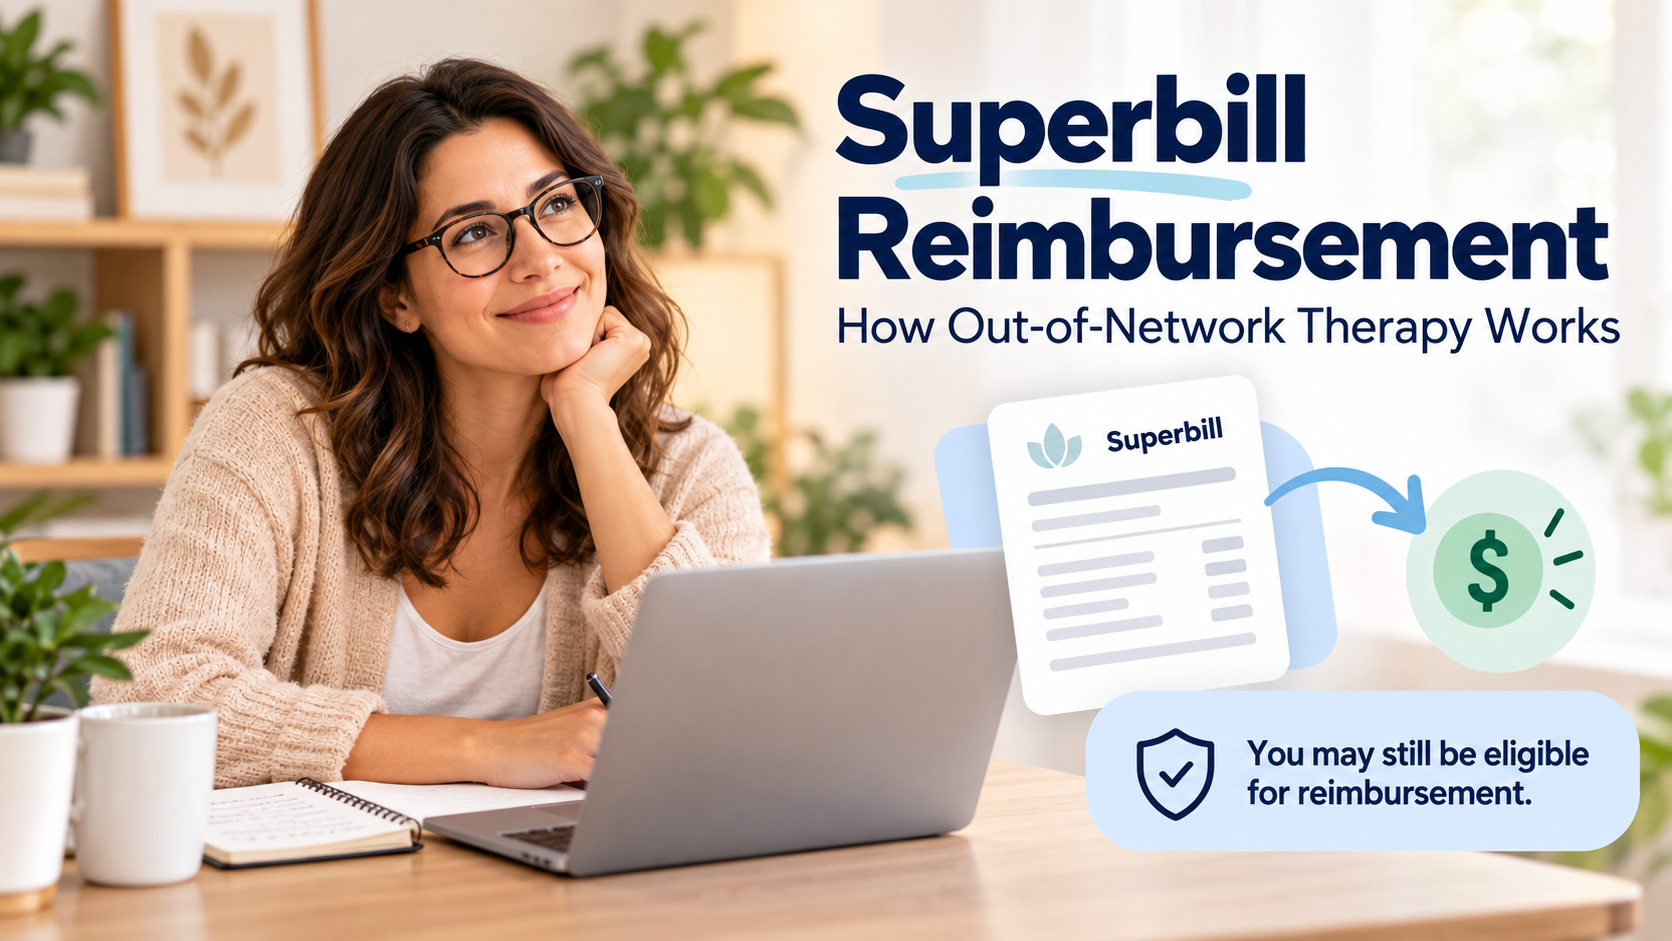
If your therapist is out of network with your health insurance plan, you may still be able to receive reimbursement for some of your therapy expenses.
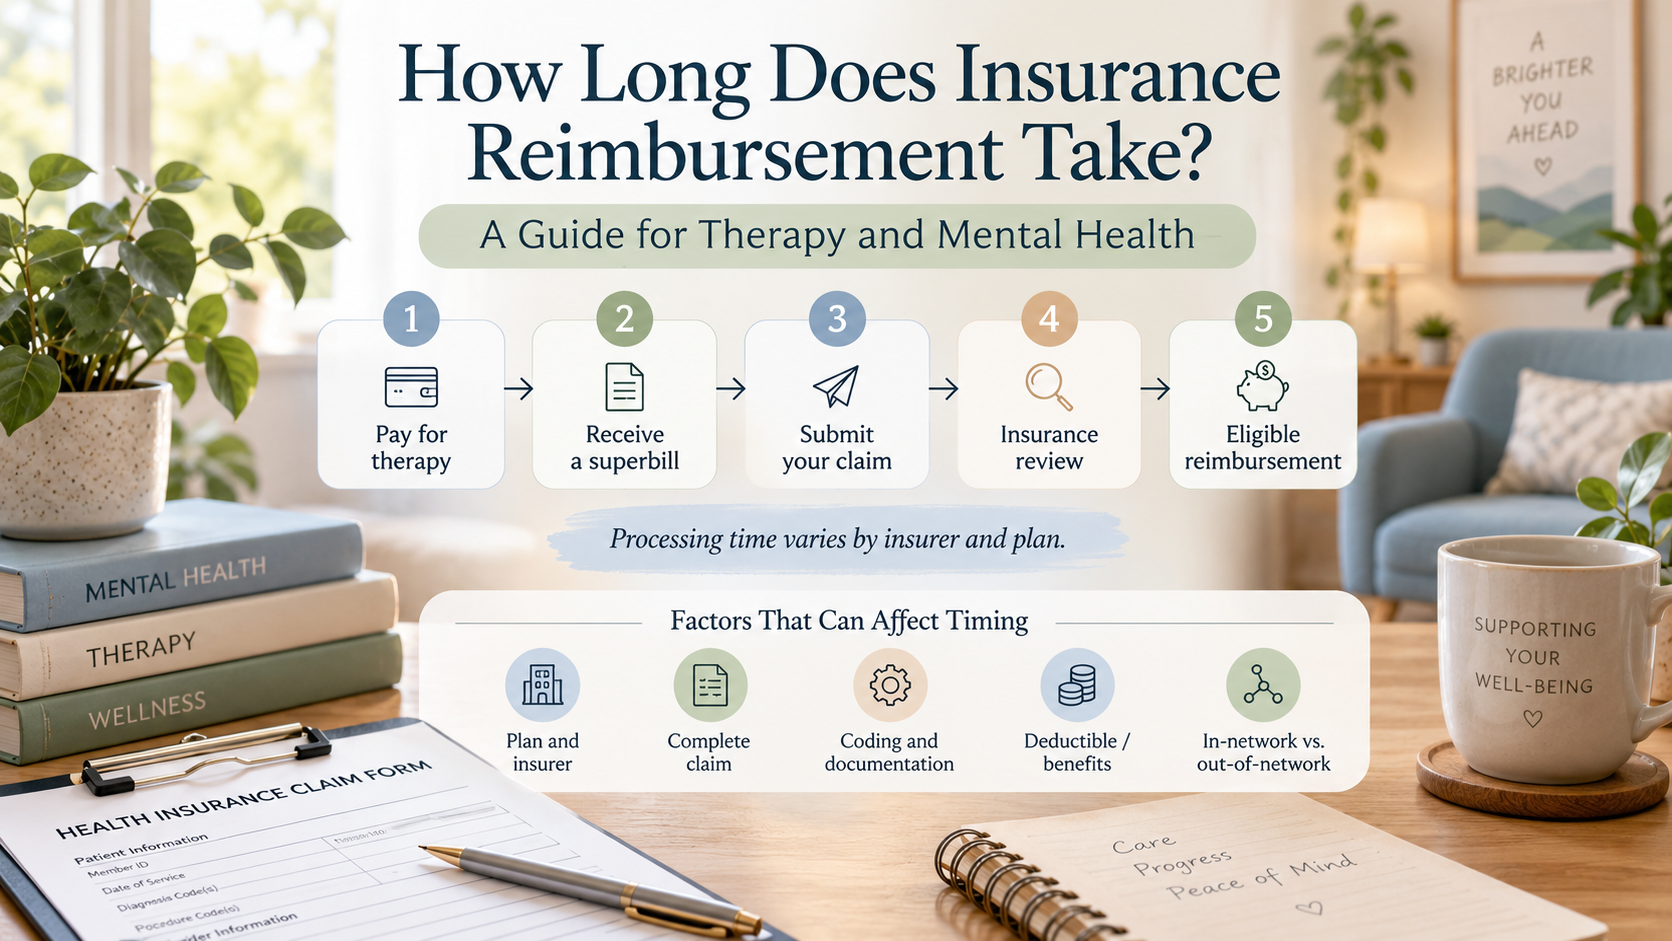
The process often involves paying your therapist directly, receiving a superbill, submitting that documentation to your insurance company, and then waiting for the insurer to process the claim and determine whether you are eligible for reimbursement.
But a superbill does not guarantee that insurance will pay you.
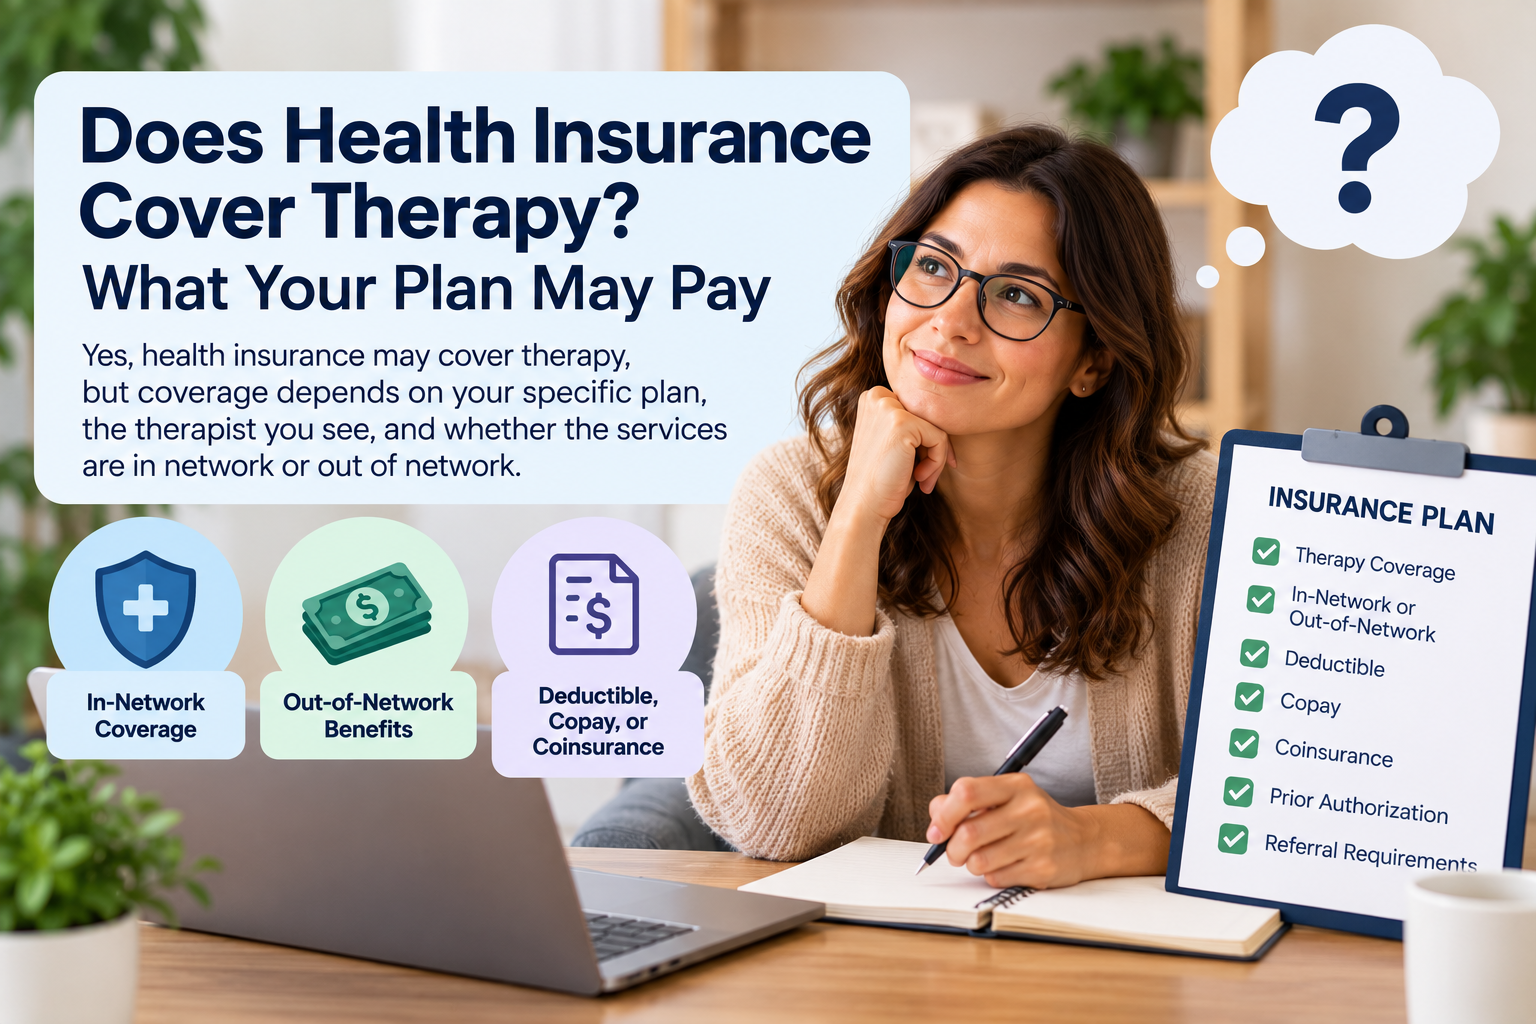
Your reimbursement depends on factors such as your plan’s out-of-network benefits, deductible, coinsurance, covered services, provider qualifications, and the insurer’s claim requirements.
Quick answer: Superbill reimbursement is the process of using a provider’s superbill to submit an out-of-network therapy claim to your health insurance company. If your plan includes out-of-network mental health benefits and the claim is eligible, your insurer may reimburse you according to the terms of your plan.
This guide explains how the process works, what a superbill does, what insurance may reimburse, and what to do if your claim is denied.
What Is Superbill Reimbursement?
Superbill reimbursement is the process of submitting documentation from a healthcare provider to an insurance company to request reimbursement for eligible services that may have been paid for out of pocket.
For therapy, the process commonly looks like this:
Therapy appointment → Pay therapist → Receive superbill → Submit claim → Insurance processes claim → EOB → Reimbursement, if eligible
A superbill is generally an itemized document containing information the insurer may need to process an out-of-network claim.
It may include:
- Patient information
- Therapist or provider information
- Provider NPI
- Date of service
- Type of service
- Procedure code
- Diagnosis code, when applicable
- Amount charged
- Amount paid
- Provider signature or other required information
The exact information needed can vary by insurer and claim type.
For a deeper explanation, see ++What Is a Superbill for Therapists?++.
How Does Superbill Reimbursement Work for Therapy?
The reimbursement process usually has several steps.
1. Check whether your plan has out-of-network benefits
Before assuming you will receive money back, check your insurance benefits.
Ask your insurer:
- Does my plan cover out-of-network mental health services?
- Does my plan cover outpatient psychotherapy?
- Is my therapist considered out of network?
- What is my out-of-network deductible?
- What is my out-of-network coinsurance?
- Is there an out-of-network reimbursement limit?
- Do I need prior authorization?
- Do I need a referral?
- Do I need to submit a specific claim form?
- Where should I submit the claim?
- Can claims be submitted online?
- Are there filing deadlines?
This step can prevent a common problem: submitting a perfectly completed superbill for a service that your particular plan does not reimburse.
For general information about health insurance coverage and benefits, visit ++HealthCare.gov++.
2. Pay for the therapy appointment
With many out-of-network arrangements, the patient pays the therapist directly.
The therapist may charge their standard private-pay rate.
For example:
Therapy session: $175
Amount paid to therapist: $175
The $175 is the provider’s charge. It does not necessarily mean the insurance company will use $175 as the amount eligible for reimbursement.
Your insurer may apply its own allowed amount or other plan-specific calculation.
3. Receive the superbill
After payment, your therapist may provide a superbill.
A superbill is different from a receipt or ordinary invoice because it is designed to contain healthcare billing information that may be useful when submitting an insurance claim.
However, a superbill by itself is generally not the same thing as an insurance claim.
Your insurer may require the superbill plus a separate claim form or electronic submission.
Read more:
4. Submit the claim to your insurance company
You typically submit the required documentation through the method specified by your insurer.
Depending on the plan, this could involve:
- An online member portal
- A mobile app
- Fax
- A designated claims process
Some insurers may have specific forms or documentation requirements.
Do not assume that every insurer uses the same process.
For a step-by-step walkthrough, see ++How to Submit Therapy Claims to Insurance++.
5. The insurer processes the claim
The insurance company reviews the claim against your plan.
The insurer may evaluate factors such as:
- Whether the service is covered
- Whether out-of-network benefits apply
- Your remaining deductible
- The insurer’s allowed amount
- Your coinsurance
- Whether the provider and service information are sufficient
- Whether authorization or other requirements apply
- Whether the claim was submitted within the applicable deadline
The insurer then determines how the claim is handled under the plan.
6. Review your explanation of benefits
After processing, you may receive an Explanation of Benefits (EOB).
An EOB can help explain:
- What was billed
- What amount the insurer considered
- What the plan allowed
- What insurance paid, if anything
- What was applied to your deductible
- What portion is your responsibility
- Whether the claim was denied or adjusted
An EOB is generally not a bill.
If the numbers do not look right, compare the EOB with your superbill and payment records and contact the insurer for clarification.
How Much Will Insurance Reimburse for an Out-of-Network Therapist?
There is no single reimbursement amount that applies to every therapy patient.
Your reimbursement depends on your insurance plan and the claim.
For example, imagine:
| Item | Example |
| Therapist’s charge | $175 |
| Amount you paid | $175 |
| Insurer’s allowed amount | $120 |
| Remaining out-of-network deductible | $0 |
| Plan coinsurance | 60% |
| Potential insurer payment | $72 |
| Potential patient cost | $103 |
This is only an illustrative example, not a prediction of what an insurer will pay.
The important point is that the therapist’s charge and the insurer’s reimbursement calculation may be different.
Your actual result could be higher, lower, or $0 depending on your plan.
For more detail, see ++How Much Does Insurance Pay for Therapy?++.
What Is the Difference Between a Superbill and Insurance Reimbursement?
A superbill is documentation.
Reimbursement is the payment you may receive from your insurance company after an eligible claim is processed.
They are related, but they are not the same thing.
| Superbill | Reimbursement |
| Created by the provider | Paid by the insurer, if eligible |
| Documents healthcare services | Represents an insurance payment |
| May support an out-of-network claim | Occurs after claim processing |
| Contains billing information | Depends on plan benefits and claim adjudication |
| Does not guarantee payment | May be $0, partial, or otherwise determined by the plan |
Think of the superbill as part of the paper trail that can support your claim.
Does a Superbill Guarantee Insurance Reimbursement?
No. A superbill does not guarantee reimbursement.
Having a properly completed superbill only means you have documentation that may be used to support an insurance claim.
Your insurer can still determine that:
- The service is not covered
- Your deductible applies
- You have no out-of-network benefits
- The provider or service does not meet a plan requirement
- Additional documentation is needed
- The claim was submitted incorrectly
- The filing deadline was missed
- Another plan requirement was not met
That’s why checking benefits before relying on reimbursement is important.
What Is an Out-of-Network Therapist?
An out-of-network therapist is a therapist who does not have a contracted provider agreement with your health insurance plan.
That does not necessarily mean insurance will not cover the therapist.
Some plans provide out-of-network benefits, while others may provide little or no coverage for out-of-network care.
This is particularly important when evaluating a therapist’s private-pay rate.
You may want to compare:
Therapist’s private-pay rate + expected insurance reimbursement
rather than looking only at the therapist’s full fee.
For a broader explanation, read ++What Is an Out-of-Network Provider?++.
Why Would Someone See an Out-of-Network Therapist?
Patients may choose an out-of-network therapist for many reasons.
For example:
The therapist is a better fit
Therapy is highly personal. A patient may prioritize a therapist’s experience, treatment approach, specialty, location, availability, or therapeutic fit.
The therapist specializes in a specific area
A therapist may have expertise that is difficult to find within a particular insurance network.
The network has limited options
A patient’s insurance network may have relatively few therapists accepting new patients in their area.
The patient prefers private-pay care
Some therapists operate primarily or exclusively outside insurance networks.
There are also administrative reasons therapists may choose not to participate in insurance networks.
See ++Why Don’t Therapists Take Insurance?++.
What Is the Out-of-Network Deductible?
An out-of-network deductible is the amount you may have to pay for covered out-of-network services before your plan begins contributing according to its terms.
For example, suppose your plan has:
- $1,000 out-of-network deductible
- 60% coinsurance after the deductible
If you have not met the deductible, an eligible therapy claim may initially be applied toward that deductible rather than generating an immediate reimbursement payment.
Once the applicable deductible has been satisfied, the plan may begin paying according to its coinsurance and other rules.
Your actual plan may work differently, so verify the details with your insurer.
What Is Out-of-Network Coinsurance?
Coinsurance is generally the percentage of an eligible healthcare cost that you are responsible for after applicable deductible requirements have been met.
For example, if a plan covers 60% of an insurer-determined allowed amount, the plan may pay 60% and leave the remaining 40% as patient responsibility.
But the calculation may not simply be:
Therapist’s charge × coinsurance percentage
The insurer may first determine an allowed amount.
That distinction can significantly affect your expected reimbursement.
Do You Have to Pay the Therapist Before Getting Reimbursed?
Often, patients using an out-of-network therapist pay the provider directly and then seek reimbursement from their insurer.
For example:
- You attend therapy.
- You pay the therapist.
- The therapist gives you a superbill.
- You submit the claim.
- The insurer processes it.
- The insurer sends an EOB.
- Any applicable reimbursement is issued according to the insurer’s process.
The exact workflow can vary by plan.
How Long Does Superbill Reimbursement Take?
There is no universal reimbursement timeline.
The time can depend on:
- How you submit the claim
- Whether the claim is complete
- Whether additional documentation is requested
- The insurer’s processing procedures
- Whether the claim is initially denied
- Whether the claim needs manual review
- Payment delivery method
If you’re waiting for reimbursement, keep your:
- Superbill
- Claim confirmation
- Submission date
- Claim number
- EOB
- Payment records
- Correspondence with the insurer
For more information, see ++How Long Does Insurance Reimbursement Take?++.
What Happens If Insurance Denies a Superbill Claim?
A denied claim does not always mean the situation is final.
First, identify why the claim was denied.
Common issues can include:
- Missing information
- Incorrect information
- Eligibility problems
- Deductible requirements
- Lack of authorization
- Service coverage limitations
- Filing deadline issues
- Provider information problems
- Incorrect claim submission
Your EOB or insurer’s claim information may explain the reason.
If the denial appears incorrect, contact the insurer and ask what information or documentation is needed and whether you have an appeal or reconsideration option under your plan.
Keep copies of everything you submit.
Can a Therapist Submit an Out-of-Network Claim for You?
Sometimes the provider may submit claims electronically or otherwise assist with the process, but this depends on the therapist’s workflow and your insurance arrangement.
With a traditional out-of-network reimbursement model, the patient may be responsible for submitting the claim.
That means the administrative workload can fall on the patient:
- Requesting the superbill
- Checking benefits
- Completing claim forms
- Uploading documents
- Tracking the claim
- Reviewing the EOB
- Following up on problems
This is one reason clear documentation from the therapist matters.
What Does a Therapist Need to Put on a Superbill?
A superbill may contain several categories of information, including:
Provider information
This can include:
- Therapist’s name
- Practice name
- Address
- Contact information
- NPI
- Other applicable provider identifiers
CMS provides information about the ++National Provider Identifier (NPI) Standard++.
Patient information
Depending on the form, this may include:
- Patient name
- Address
- Date of birth
- Insurance information, when applicable
Service information
A superbill may identify:
- Date of service
- Type of service
- Procedure code
- Diagnosis code, when applicable
- Amount charged
- Amount paid
Current coding requirements and applicable codes should be verified against authoritative sources and payer requirements.
For coding references:
- ++CMS ICD-10 information++
- ++CDC ICD-10-CM++
- ++AMA CPT++
Superbill Reimbursement Example
Consider a hypothetical patient who sees an out-of-network therapist.
The therapist charges $180 per session.
The patient’s plan includes out-of-network mental health benefits.
Appointment
The patient pays:
$180
Superbill
The therapist provides a superbill documenting the session and applicable billing information.
Claim
The patient submits the required documentation to the insurer.
Insurance processing
The insurer determines the claim’s eligible amount according to the patient’s plan.
Suppose, purely for illustration, the insurer determines that $130 is the applicable allowed amount and the plan provides 60% reimbursement after the applicable deductible has been satisfied.
The potential insurer payment would be:
$130 × 60% = $78
The patient’s effective cost could therefore be:
$180 − $78 = $102
Again, this is an example—not a typical or guaranteed reimbursement amount.
The actual calculation depends on the patient’s insurance plan and claim.
How Can Patients Make Superbill Reimbursement Easier?
A few habits can reduce administrative headaches.
Before therapy
Confirm:
- Out-of-network benefits
- Deductible
- Coinsurance
- Covered services
- Authorization requirements
- Claim submission process
- Filing deadline
After each appointment
Keep:
- Receipt or payment confirmation
- Superbill
- Appointment date
- Amount paid
After submitting a claim
Record:
- Submission date
- Claim number
- Confirmation number
- Expected follow-up date
When the EOB arrives
Compare:
- Amount charged
- Amount allowed
- Amount applied to deductible
- Insurance payment
- Patient responsibility
If something does not make sense, ask the insurer for clarification.
How Can Therapists Make Superbill Reimbursement Easier for Clients?
Therapists can reduce friction by creating consistent billing workflows.
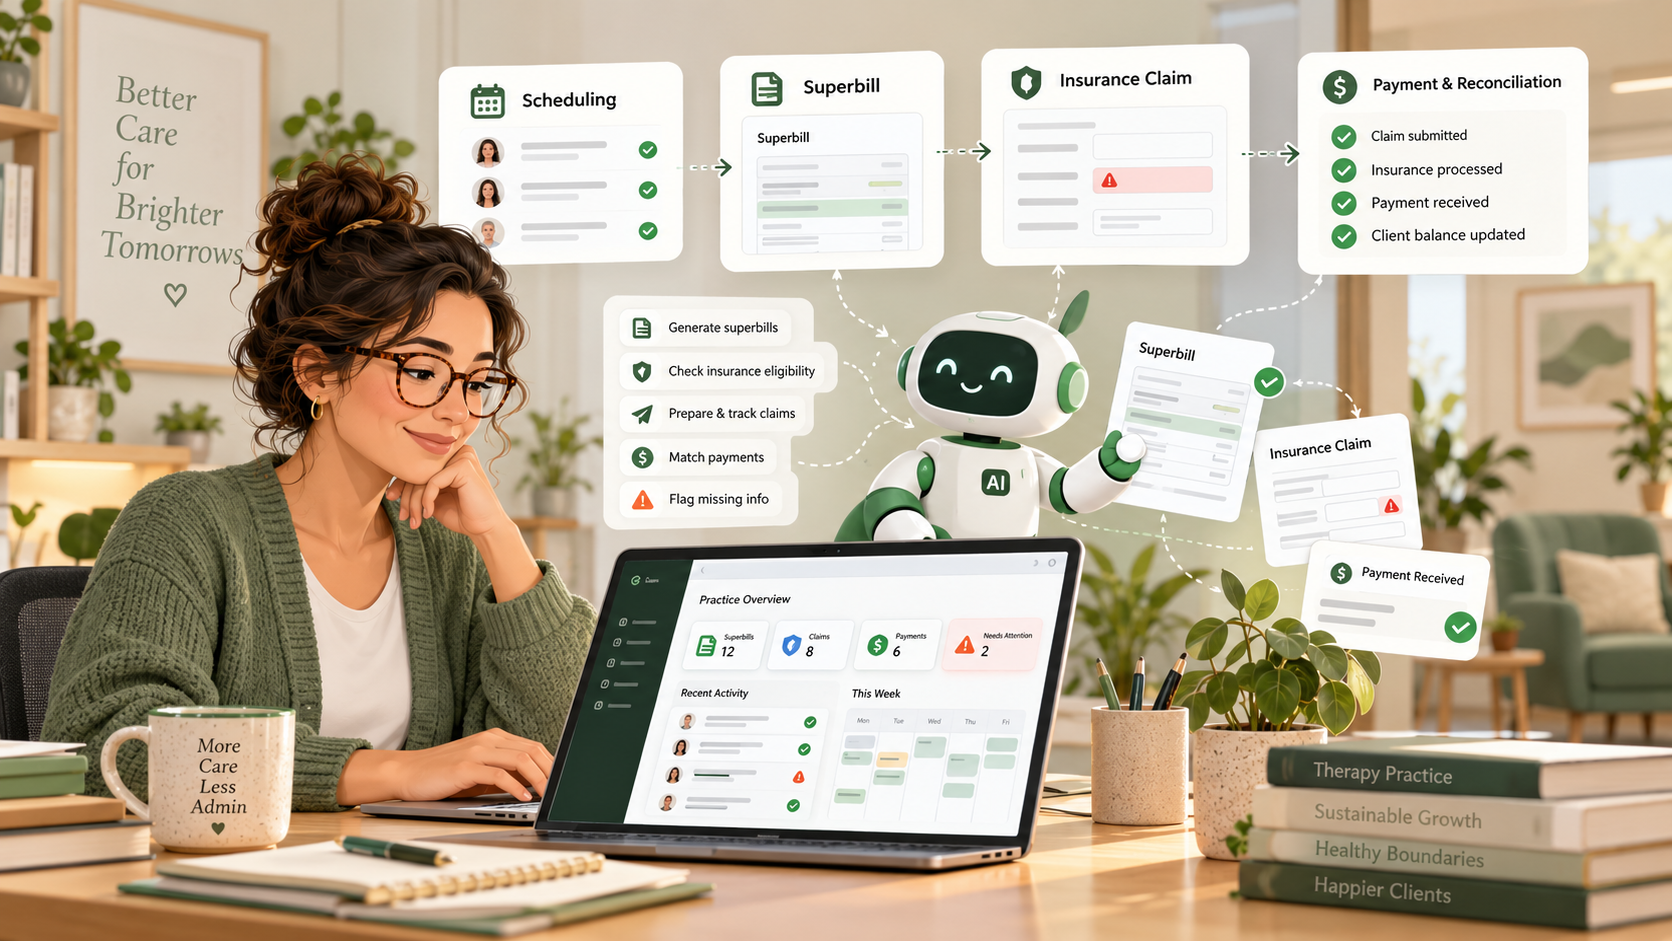
Instead of manually recreating every superbill, a practice can use structured billing information to generate documentation consistently.
Useful workflow improvements can include:
- Standardized patient records
- Consistent provider information
- Structured service documentation
- Automated superbill generation
- Payment tracking
- Claim-related documentation
- Status tracking
- Error checking
- Secure handling of patient information
This is where billing software can become more than a convenience—it can reduce repetitive administrative work.
See ++Mental Health Billing Software for Therapists++ for more information about how DeputyCare approaches billing and insurance administration.
Can AI Help With Superbill and Insurance Administration?
AI and automation can potentially reduce repetitive administrative work around therapy billing, documentation, and insurance workflows.
For example, automation may help practices:
- Organize billing information
- Identify missing fields
- Generate repetitive documentation
- Reduce manual data entry
- Track administrative tasks
- Surface potential workflow errors
- Standardize recurring processes
AI should not be treated as a replacement for professional judgment, payer requirements, or appropriate privacy and security safeguards.
Whether an AI-enabled workflow is appropriate for protected health information also depends on how the system is implemented, what data it handles, what safeguards are in place, and the applicable contractual and compliance requirements.
Read more about this topic in ++How AI Is Transforming Therapy Superbill and Insurance Workflows++.
Superbill Reimbursement Checklist
Use this checklist when navigating out-of-network therapy reimbursement.
Before your appointment
- Confirm your therapist’s network status
- Check out-of-network mental health benefits
- Check your out-of-network deductible
- Check coinsurance
- Ask about authorization requirements
- Confirm the claim submission process
- Check the filing deadline
After your appointment
- Pay the therapist
- Obtain your superbill
- Keep proof of payment
- Review the superbill for obvious errors
When submitting
- Complete the insurer’s required claim form
- Attach the superbill if required
- Submit through the insurer’s approved channel
- Save your confirmation
- Record the claim number
After processing
- Review the EOB
- Compare the EOB with your records
- Confirm any reimbursement
- Contact the insurer about discrepancies
- Appeal or request reconsideration if appropriate
Frequently Asked Questions About Superbill Reimbursement
What is superbill reimbursement?
Superbill reimbursement is the process of submitting a therapist’s superbill and any other required claim documentation to an insurance company to request reimbursement for eligible out-of-network services.
Does a superbill mean insurance will pay?
No. A superbill documents services but does not guarantee reimbursement. Payment depends on your insurance plan and how the insurer processes the claim.
How much does insurance reimburse for out-of-network therapy?
There is no universal reimbursement amount. The amount can depend on your plan’s out-of-network benefits, deductible, allowed amount, coinsurance, covered services, and other requirements.
Do all insurance plans reimburse out-of-network therapy?
No. Some plans provide out-of-network benefits, while others may provide limited or no coverage. Check your specific plan.
Can I get reimbursed for therapy if my therapist is out of network?
Possibly. If your plan includes applicable out-of-network mental health benefits, you may be able to submit claims for eligible services.
Do I need a superbill to get reimbursed?
Not necessarily in every situation. Your insurer determines what documentation is required. A superbill is commonly used to document out-of-network healthcare services, but you should verify the requirements with your insurer.
Is a superbill the same as a claim?
No. A superbill is provider documentation. An insurance claim is the request submitted to the insurer for processing. Depending on the insurer, the superbill may be attached to or used as supporting documentation for the claim.
How long does superbill reimbursement take?
There is no universal timeline. Processing time depends on the insurer, submission method, completeness of the claim, and whether additional review is required.
What if my superbill claim is denied?
Review the denial reason, contact your insurer if clarification is needed, and determine whether the claim can be corrected, reconsidered, or appealed under your plan.
Can therapists automate superbills?
Yes. Billing and practice-management software can automate parts of the superbill workflow, such as pulling structured information into standardized documentation and reducing repetitive data entry.
The Bottom Line
Superbill reimbursement can make out-of-network therapy more affordable when your health insurance plan provides applicable out-of-network benefits.
The basic process is:
Check benefits → Pay therapist → Get superbill → Submit claim → Review EOB → Receive reimbursement if eligible
The most important step is to verify your specific insurance benefits before assuming reimbursement will occur.
Your therapist’s fee, your insurer’s allowed amount, your deductible, coinsurance, coverage rules, and claim requirements can all affect what you ultimately pay.
For therapists, the process also highlights why accurate, consistent billing workflows matter. A well-organized system can make it easier to produce documentation, reduce repetitive administrative work, and support a smoother patient experience.
Related Resources
Superbill guides
- ++Superbill for Therapists++
- ++Mental Health Superbill Template++
- ++How to Create a Superbill for Therapy++
Insurance and reimbursement
- ++What Is an Out-of-Network Provider?++
- ++How to Submit Therapy Claims to Insurance++
- ++How Much Does Insurance Pay for Therapy?++
- ++How Long Does Insurance Reimbursement Take?++
- ++Why Don’t Therapists Take Insurance?++