How Much Does Insurance Pay for Therapy? What to Expect
If you’re wondering how much insurance pays for therapy, there is no single amount that applies to every therapist, insurance company, or patient.
Insurance payment depends on factors such as the patient’s health plan, whether the therapist is in-network or out-of-network, the negotiated or allowed amount, deductible, copay, coinsurance, and the type of therapy service provided.
For example, a therapist might charge $150 for a session, but that does not necessarily mean the insurance company will pay $150. The insurer may determine a different allowed amount, and the patient’s plan may require the patient to pay part or all of that amount.
This guide explains how therapy insurance payments work, what determines reimbursement, what patients may have to pay, and how therapists can make insurance billing and superbill workflows easier.
Quick answer: Insurance does not pay one standard rate for therapy. The amount paid depends on the patient’s insurance benefits, the therapist’s network status, the service provided, the insurer’s allowed amount, and whether the patient has met their deductible or owes a copay or coinsurance.
How Much Does Insurance Pay for a Therapy Session?
Insurance can pay different amounts for the same type of therapy service.
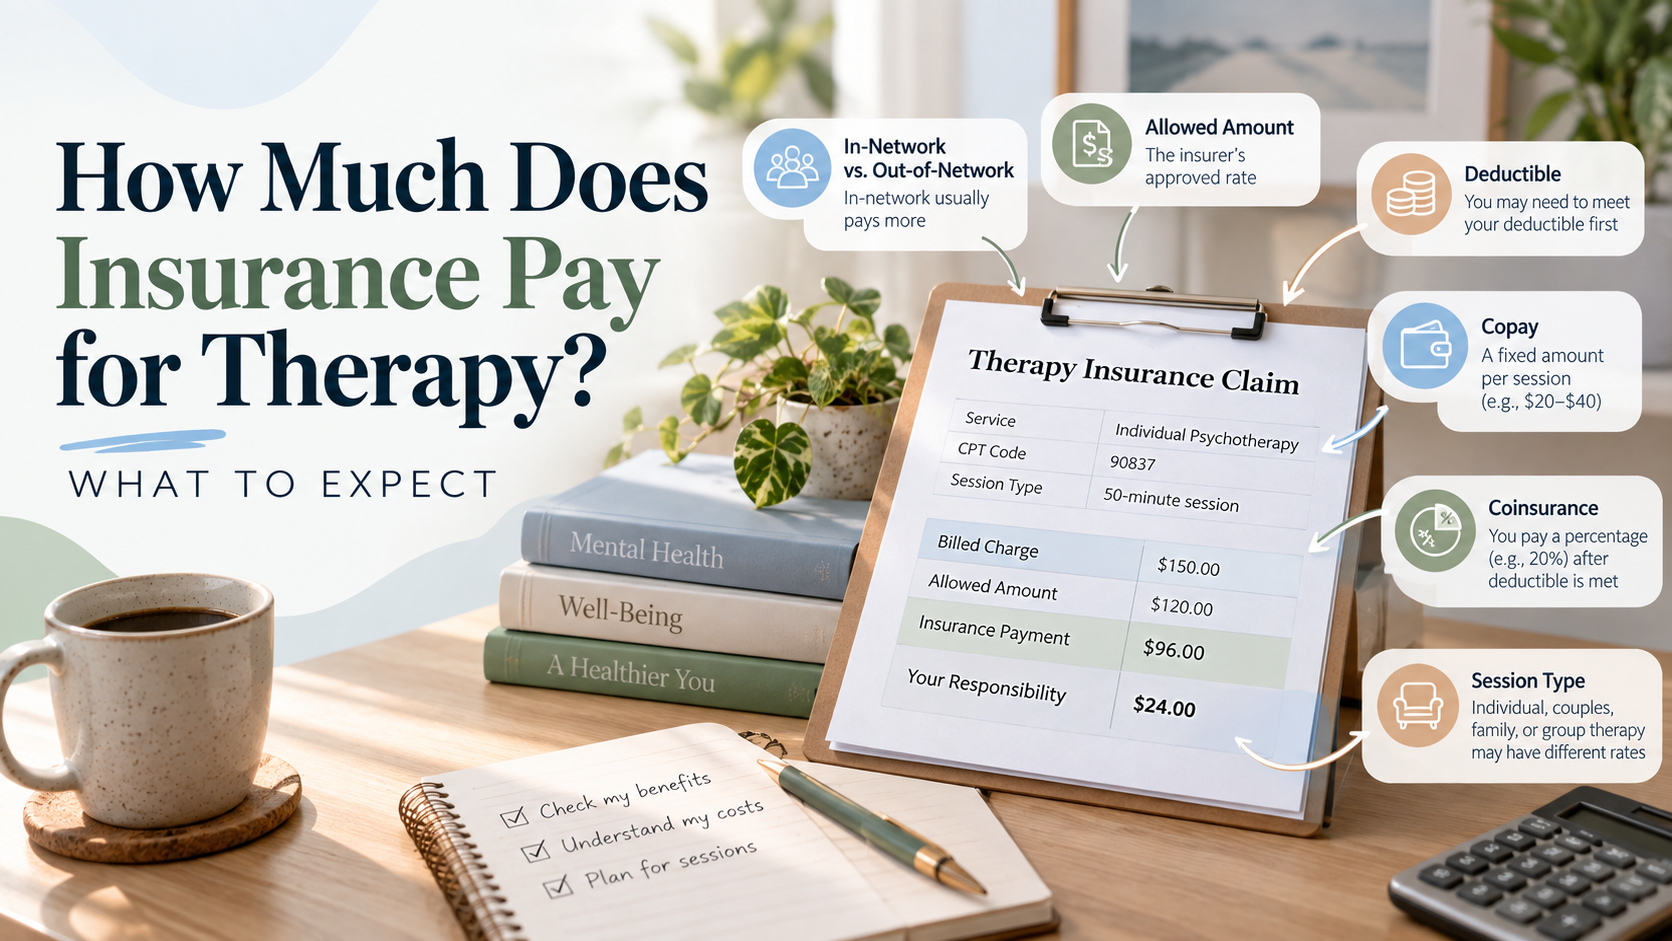
A simplified example might look like this:
| Example | Amount |
| Therapist’s listed charge | $150 |
| Insurance-approved/allowed amount | $120 |
| Insurance pays | $96 |
| Patient coinsurance | $24 |
| Patient responsibility | $24 |
This is only an illustrative example, not a typical or guaranteed reimbursement rate.
The actual numbers depend on the patient’s specific insurance plan and the provider’s agreement with the insurer.
In another situation, the patient may have a deductible that has not yet been met. In that case, the patient could be responsible for some or all of the allowed amount rather than simply paying a fixed percentage.
What Determines How Much Insurance Pays for Therapy?
Several factors can affect the amount an insurance plan pays.
1. Whether the Therapist Is In-Network
An in-network therapist generally has a contractual relationship with the insurance company.
The insurer and provider may have agreed on specific reimbursement amounts for covered services.
For an in-network visit, the patient generally pays the applicable cost-sharing amount under the plan, while the insurer pays its portion according to the plan and provider agreement.
An out-of-network therapist does not have the same in-network contractual arrangement.
Some insurance plans provide out-of-network mental health benefits, while others may provide limited or no out-of-network coverage.
That distinction can significantly affect what both the insurer and patient pay.
2. The Insurance Plan’s Allowed Amount
An insurer may determine an allowed amount for a covered service.
The allowed amount is not necessarily the same as the therapist’s standard fee.
For example:
Therapist’s charge: $175
Plan’s allowed amount: $125
The insurer may calculate its payment based on the applicable $125 allowed amount rather than the therapist’s $175 listed charge.
The exact terminology and calculation can vary by insurance plan.
3. The Patient’s Deductible
A deductible is the amount a patient may have to pay for covered healthcare services before the insurance plan begins paying according to its benefits.
Suppose:
- Therapy charge: $150
- Allowed amount: $120
- Remaining deductible: $500
Depending on the plan’s rules, the patient may be responsible for some or all of the $120 allowed amount until the deductible is satisfied.
Once the deductible has been met, the patient’s cost-sharing may change.
Patients should check their specific plan documents rather than assuming that every therapy visit will be covered at the same rate.
4. Copays and Coinsurance
After applicable plan requirements are met, the patient may still have cost sharing.
Copay
A copay is generally a fixed amount the patient pays for a covered service.
For example:
Therapy visit: $150
Patient copay: $30
Insurance payment: Based on the plan’s applicable benefit and allowed amount
Coinsurance
Coinsurance is generally a percentage of the applicable cost or allowed amount that the patient is responsible for.
For example:
Allowed amount: $120
Patient coinsurance: 20%
Patient responsibility: $24
The insurer would generally pay the remaining covered portion, subject to the plan’s rules.
Does Insurance Cover Therapy?
Many health insurance plans cover some mental health services, but coverage varies by plan.
Patients should verify:
- Whether mental health services are covered
- Whether outpatient therapy is covered
- Whether the therapist is in-network
- Whether out-of-network benefits are available
- Whether a deductible applies
- Whether a copay or coinsurance applies
- Whether there are visit limits or other restrictions
- Whether prior authorization is required
- How claims or reimbursement requests must be submitted
For information about health insurance coverage and consumer protections, see ++HealthCare.gov++.
Federal mental health parity requirements may also apply to certain health plans. The ++U.S. Department of Labor’s Mental Health Parity and Addiction Equity Act resources++ provide additional information.
How Much Does Insurance Pay for Out-of-Network Therapy?
Out-of-network reimbursement works differently from in-network billing.
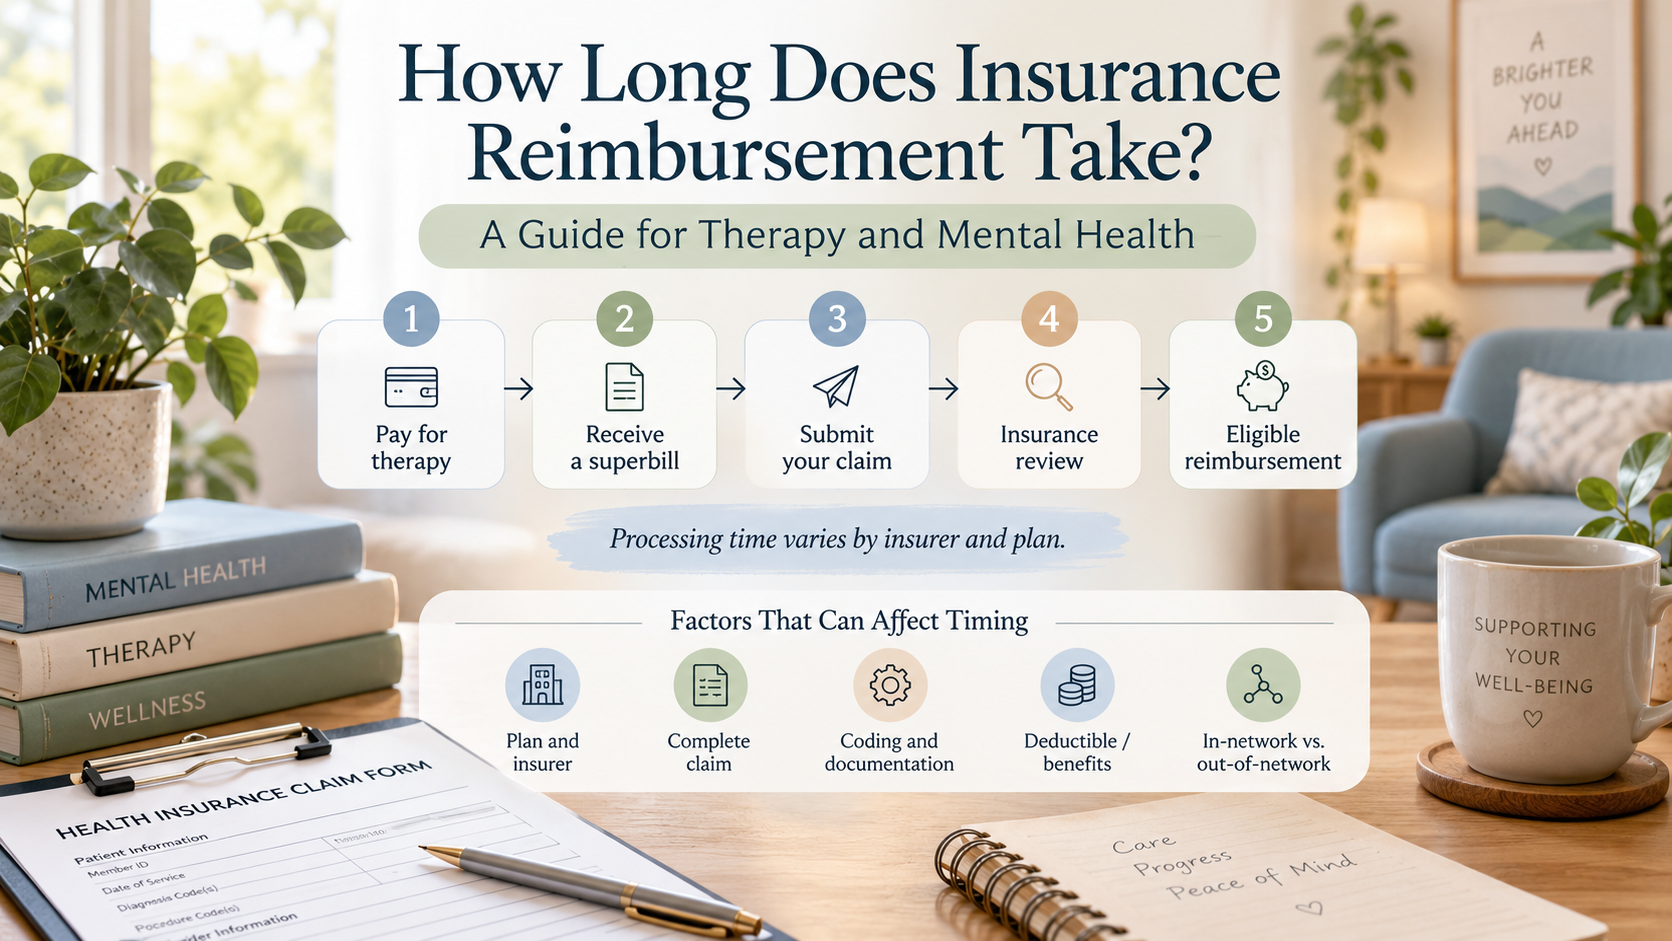
If a therapist is out of network, the patient may need to:
- Pay the therapist.
- Receive a superbill.
- Submit the superbill and any required claim form to the insurance company.
- Wait for the insurer to process the claim.
- Receive reimbursement if the service is eligible under the plan.
For example:
Therapist charges: $150
Insurance allowed amount: $120
Plan reimbursement: 70%
Potential reimbursement: $84
Again, this is an illustrative calculation only. It is not a prediction of what an insurer will pay.
The actual reimbursement may be affected by the deductible, plan rules, allowed amount, exclusions, claim requirements, and other factors.
For more information about superbills, see ++Superbill for Therapists: Complete Guide++.
What Is a Superbill and How Does It Affect Therapy Reimbursement?
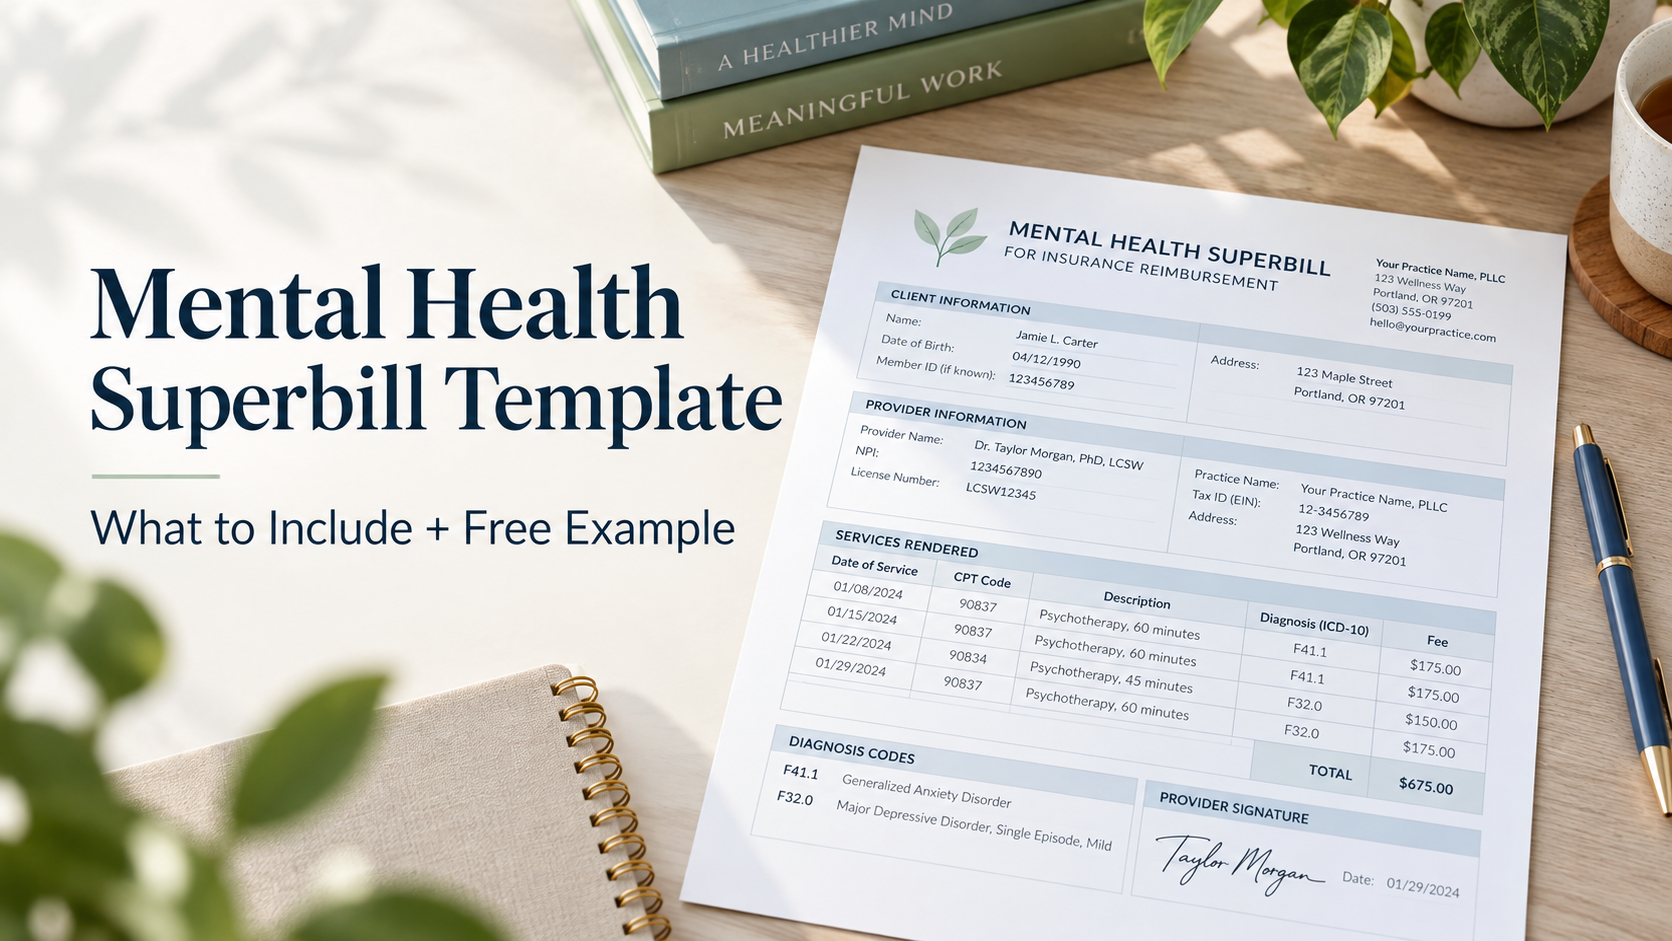
A superbill is an itemized document that summarizes healthcare services provided to a patient.
For therapy, it may contain information such as:
- Provider name
- Provider credentials
- NPI
- Practice information
- Patient information
- Date of service
- Procedure/CPT code
- Diagnosis information
- Charge
- Payment information
Patients may use a superbill when requesting reimbursement for eligible out-of-network services.
A superbill itself does not determine how much insurance will pay.
The insurer determines reimbursement based on the patient’s plan and the information submitted with the claim.
Learn more in our guide to ++how to create a superbill for therapy++.
Does Insurance Pay the Therapist or the Patient?
It depends on the billing arrangement.
In-network therapy
With an in-network therapist, the provider commonly submits the claim directly to the insurance company.
The insurer pays the provider according to the applicable provider agreement and the patient’s benefits, while the patient pays their required cost sharing.
Out-of-network therapy
With an out-of-network therapist, the patient may pay the therapist directly and then submit a claim for reimbursement.
If the claim is eligible, the insurer may reimburse the patient according to the plan’s out-of-network benefits.
The exact process varies by insurance company and health plan.
Why Can Two Insurance Plans Pay Different Amounts for Therapy?
Two patients can receive the same type of therapy from the same therapist but have different insurance reimbursement outcomes.
That’s because each patient may have different:
- Insurance companies
- Insurance plans
- Deductibles
- Copays
- Coinsurance
- Out-of-network benefits
- Allowed amounts
- Coverage rules
- Claim requirements
For example:
| Patient A | Patient B | |
| Therapist’s charge | $150 | $150 |
| Allowed amount | $120 | $100 |
| Deductible status | Met | Not met |
| Cost sharing | 20% coinsurance | Patient responsibility under deductible |
| Patient payment | Depends on plan | Depends on plan |
The therapist’s listed price alone therefore cannot tell you how much an insurer will pay.
How Much Does Insurance Pay for Group Therapy?
Group therapy can have different billing and reimbursement rules from individual psychotherapy.
The amount an insurer pays can depend on:
- The specific group service
- Applicable procedure code
- Provider credentials
- Insurance plan
- Network status
- Allowed amount
- Deductible
- Copay or coinsurance
- Coverage requirements
SpyFu data shows search demand specifically around “how much does insurance pay for group therapy,” indicating that this is an important supporting question for this topic.
Patients should confirm their plan’s benefits before assuming that group therapy will be reimbursed at the same level as individual therapy.
How Much Does Insurance Pay for a Therapy Intake?
An initial therapy appointment or intake may be billed differently from a standard follow-up psychotherapy session.
The reimbursement amount can depend on:
- The service actually provided
- The applicable procedure code
- Provider type
- Insurance plan
- Network status
- Allowed amount
- Patient benefits
There is therefore no universal insurance payment for a therapy intake.
Patients and providers should verify the applicable benefits and billing requirements rather than relying on a general dollar amount.
Why Does the Therapist’s Price Differ From the Insurance Payment?
A therapist’s charge and an insurer’s payment are different concepts.
A therapist may charge $200 for a session.
The insurer may determine an allowed amount of $140.
The patient’s plan may then specify that the insurer covers a percentage of the applicable amount after the deductible.
This means:
Therapist’s charge ≠ insurance allowed amount ≠ insurance payment
Understanding this distinction can make an insurance explanation much easier.
What Does “Allowed Amount” Mean for Therapy?
The allowed amount is generally the maximum amount a health plan recognizes for a covered service under the applicable plan rules.
For an in-network provider, the allowed amount may be based on the negotiated rate.
For an out-of-network provider, the plan may use a different methodology to determine the amount it recognizes for reimbursement.
The terminology and calculation can differ by insurer and plan.
Patients should check their Explanation of Benefits (EOB) and plan documents for the amount used in their specific claim.
What Is an Explanation of Benefits?
An Explanation of Benefits (EOB) is a document from an insurance company explaining how a claim was processed.
An EOB can help show:
- The service billed
- The amount submitted
- The amount allowed
- What insurance paid
- What the patient may owe
- Deductible amounts
- Coinsurance
- Other claim information
An EOB is generally not a bill.
If the numbers are confusing, patients can contact their insurer for an explanation of how the claim was processed.
How Can Patients Find Out Exactly How Much Their Insurance Will Pay?
The most reliable source is the patient’s insurance company and plan documentation.
Before starting therapy, ask the insurer:
- Is outpatient mental health therapy covered?
- Is my therapist in network?
- Do I have out-of-network mental health benefits?
- What is my deductible?
- Have I met my deductible?
- What is my copay?
- What is my coinsurance?
- How is the allowed amount determined?
- Do I need prior authorization?
- How do I submit an out-of-network claim?
- Do I need a superbill?
- Are there any limitations on covered therapy services?
Patients can also ask the therapist’s office about the provider’s fee and billing process.
Important: A therapist’s estimate of insurance coverage is not a guarantee of payment. The insurer determines coverage and reimbursement according to the patient’s plan.
What Should Therapists Know About Insurance Reimbursement?
Therapists who accept insurance or provide superbills need to distinguish between:
- Their standard charge
- Contracted or allowed amounts
- Insurance payments
- Patient responsibility
- Deductibles
- Copays
- Coinsurance
- Out-of-network reimbursement
Clear billing communication can help patients understand what they may owe and what they may need to submit to their insurer.
For out-of-network practices, an accurate superbill workflow is particularly important.
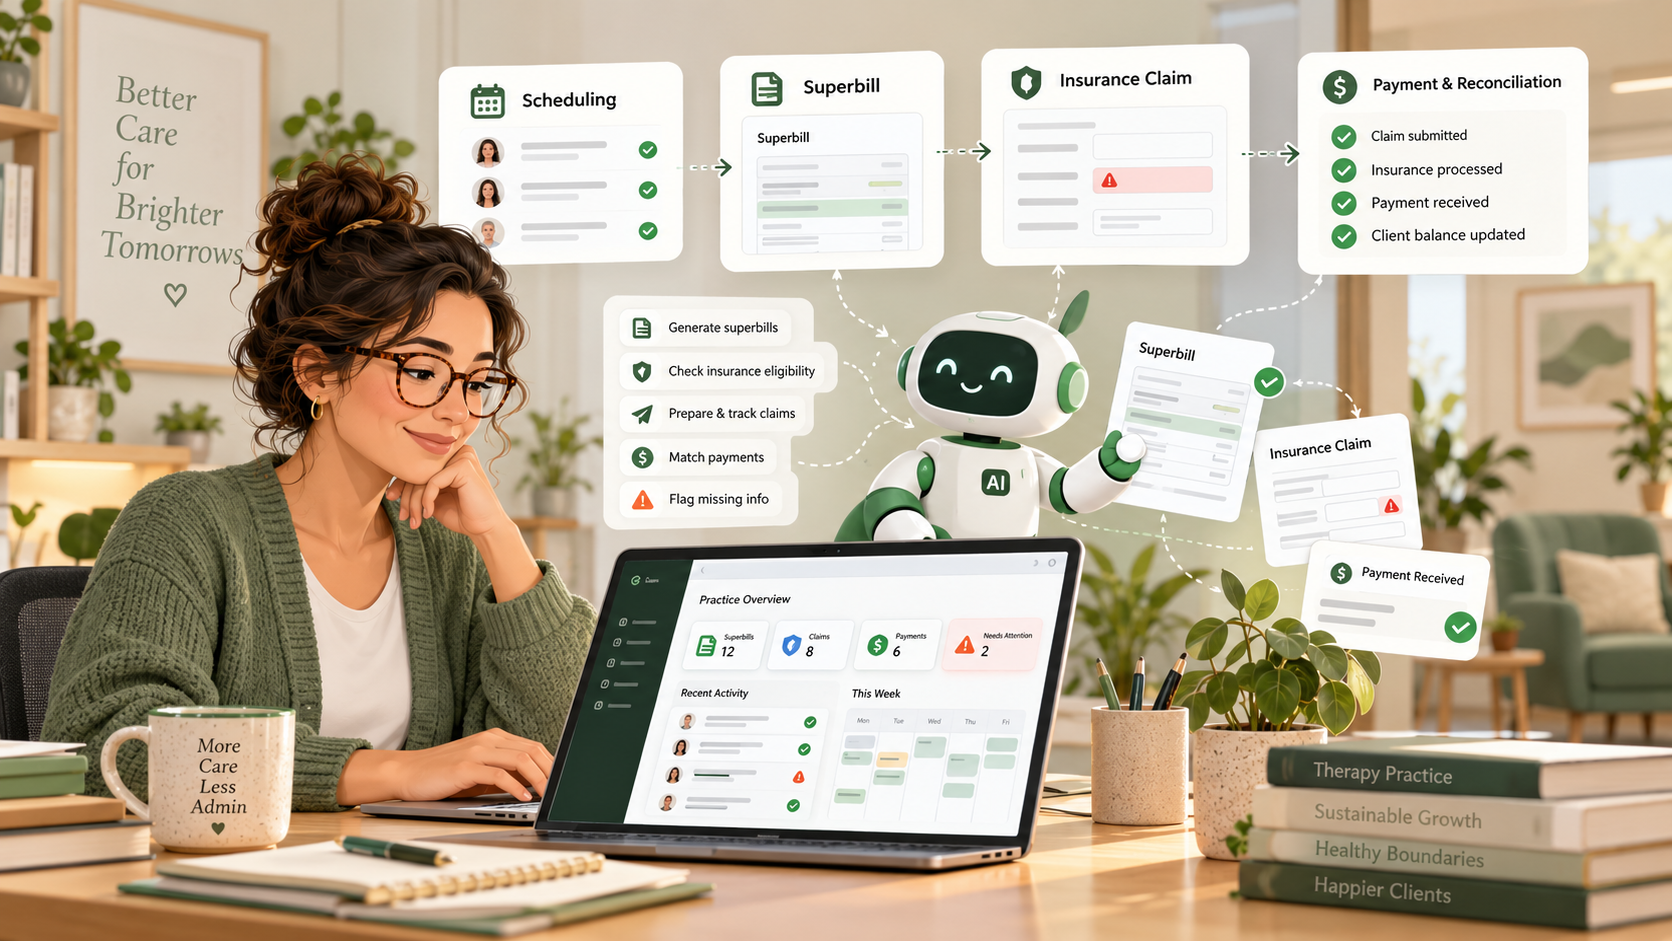
How Therapy Billing Software Can Help
Insurance administration can create significant repetitive work for therapy practices.
A practice may need to manage:
- Patient information
- Provider information
- Appointment dates
- Services
- Procedure codes
- Diagnosis information
- Charges
- Payments
- Superbills
- Insurance documentation
Billing and practice-management software can help organize this information and reduce repetitive manual entry.
For practices with a significant out-of-network population, automation can make the superbill and reimbursement workflow more consistent.
How DeputyCare Helps With Therapy Billing and Insurance Administration
DeputyCare focuses on administrative workflows around billing, insurance, superbills, and automation.
For therapy practices, streamlining repetitive administrative processes can make it easier to manage billing information and support patients who need documentation for insurance reimbursement.
Rather than treating every superbill or insurance workflow as a manual task, software can help practices organize recurring administrative processes.
++Learn more about DeputyCare →++
Frequently Asked Questions
How much does insurance usually pay for therapy?
There is no single standard insurance payment for therapy. The amount depends on the patient’s plan, therapist’s network status, allowed amount, deductible, copay, coinsurance, and the specific service provided.
Does insurance pay for therapy?
Many insurance plans cover eligible mental health services, but coverage varies. Patients should verify their benefits, network status, cost sharing, and any authorization requirements with their insurer.
How much does insurance pay for a therapy session?
The amount can vary significantly. Insurance payment is generally based on the applicable plan rules, allowed amount, network status, and the patient’s cost-sharing requirements.
How much does insurance pay for out-of-network therapy?
It depends on the plan’s out-of-network benefits. Some plans reimburse a percentage of an allowed amount after a deductible, while other plans may have different rules or no out-of-network coverage.
Does insurance pay the therapist directly?
For in-network care, the therapist commonly submits the claim and receives payment from the insurer, with the patient responsible for applicable cost sharing. For out-of-network care, the patient may pay the therapist and submit a claim for reimbursement.
What is the allowed amount for therapy?
The allowed amount is generally the amount an insurance plan recognizes for a covered healthcare service under its applicable rules. It may differ from the therapist’s listed charge.
Why does my therapist charge more than insurance pays?
A therapist’s standard charge does not necessarily equal the amount an insurer recognizes or pays. Insurance reimbursement can be based on a contracted or otherwise determined allowed amount.
How can I find out what my insurance will pay for therapy?
Contact your insurance company and ask about mental health benefits, network status, deductible, copay, coinsurance, out-of-network reimbursement, and the allowed amount for the relevant service.
Can I get reimbursed for out-of-network therapy?
Possibly. Whether you can receive reimbursement depends on your insurance plan’s out-of-network mental health benefits and claim requirements.
Do I need a superbill for out-of-network therapy?
Many out-of-network reimbursement workflows use a superbill, although the exact requirements vary by insurer. Check your plan’s claim-submission instructions.
Therapy Insurance Payment Example
Consider this simplified example:
Therapist’s charge: $175
Insurance-recognized amount: $125
Patient’s applicable coinsurance: 20%
If the service is covered and the deductible has already been satisfied, the patient’s coinsurance could be:
$125 × 20% = $25
The insurer could then pay the remaining $100 of the recognized amount.
But this does not mean the patient will always pay $25.
If the deductible has not been satisfied, the patient’s responsibility could be different.
Likewise, an out-of-network plan may calculate reimbursement differently.
The example is intended to explain the mechanics—not predict an actual insurance payment.
Insurance Payment vs. Therapist Fee: The Key Difference
The easiest way to understand therapy reimbursement is to separate three numbers:
1. Therapist’s charge
What the therapist bills or charges for the service.
2. Allowed or recognized amount
The amount the insurance plan uses when determining its benefit, according to the plan’s rules.
3. Insurance payment
The portion of the applicable amount that the insurer pays after considering the patient’s benefits and cost sharing.
These numbers can be different.
Charge → Allowed amount → Insurance payment + Patient responsibility
Understanding this sequence can prevent many common misunderstandings about therapy costs.
Final Takeaway
So, how much does insurance pay for therapy?
There is no universal dollar amount.
Insurance reimbursement depends on the patient’s specific plan, the therapist’s network status, the service provided, the applicable allowed amount, deductible, copay or coinsurance, and the insurer’s claim rules.
If you’re a patient, the best way to determine your expected cost is to contact your insurance company before beginning treatment.
If you’re a therapist, maintaining accurate billing records and a consistent insurance and superbill workflow can make reimbursement administration easier for both your practice and your patients.
For practices that regularly manage out-of-network therapy, ++learn more about superbills for therapists++ and how ++therapy superbills can be created and managed++.
Related Reading
- ++Superbill for Therapists: Complete Guide++
- ++How to Create a Superbill for Therapy++
- ++Mental Health Superbill Template: What to Include + Free Example++
- ++Why Don’t Therapists Take Insurance?++
- ++How AI Is Transforming Therapy Superbill and Insurance Workflows++
Authoritative Resources
For patients and providers looking for additional information about health insurance and mental health coverage:
- ++HealthCare.gov — Health Insurance Coverage++
- ++U.S. Department of Labor — Mental Health Parity++
- ++CMS — National Provider Identifier Standard++
- ++HHS — HIPAA for Professionals++
This article provides general educational information and is not insurance, legal, medical, or financial advice. Insurance benefits, reimbursement methodologies, deductibles, cost sharing, and claim requirements vary by plan. Patients should verify coverage and reimbursement directly with their insurance company.