Is Therapy Covered by Insurance? A Guide to Therapy Insurance Coverage
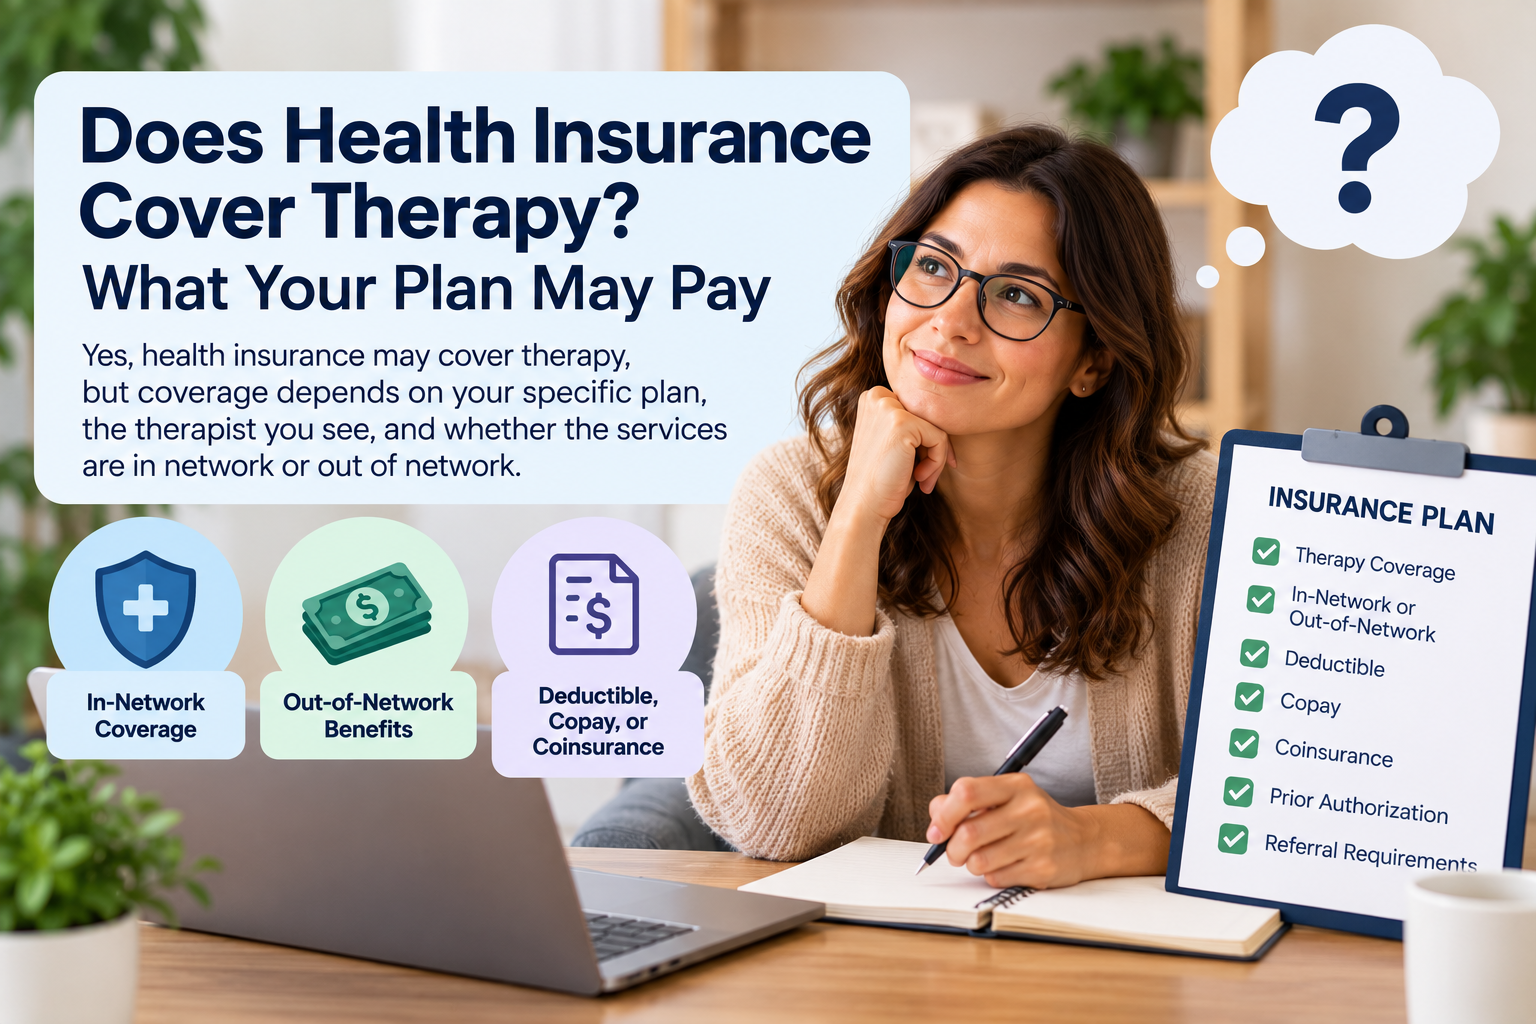
Yes, therapy may be covered by health insurance, but coverage depends on your specific health plan, the type of therapy, your therapist’s network status, and your plan’s deductible, copay, or coinsurance.
Many people assume that having health insurance automatically means therapy will be fully covered. That’s not necessarily the case.
Your plan may cover therapy provided by an in-network therapist while offering different benefits for an out-of-network therapist. Some plans may also require a deductible, authorization, referral, or other conditions before coverage applies.
If you’re considering therapy, understanding how insurance coverage works can help you estimate your potential out-of-pocket cost before your first appointment.
This guide explains what therapy insurance coverage means, how in-network and out-of-network therapy differ, how reimbursement works, and what you can do if your therapist doesn’t accept your insurance.
Is Therapy Covered by Health Insurance?
Therapy is covered by many health insurance plans, but the amount you pay depends on your individual benefits.
Coverage can vary based on:
- Your insurance plan
- Whether your therapist is in network
- Whether your plan provides out-of-network benefits
- Your deductible
- Your copay
- Your coinsurance
- The type of mental health service
- Whether prior authorization is required
- Whether the provider meets your plan’s requirements
- Whether the service is considered covered under your plan
Because plans differ, the safest approach is to verify your benefits directly with your insurance company.
For general information about health insurance coverage, visit ++HealthCare.gov++.
Does Health Insurance Cover Therapy?
In many cases, yes.
Health insurance plans can cover mental health and behavioral health services, but coverage does not necessarily mean that your insurance company will pay the entire cost of therapy.
For example, your plan might cover an in-network therapy appointment with a fixed copay.
Another plan might require you to satisfy a deductible before the insurer contributes.
An out-of-network plan might reimburse a percentage of an insurer-determined allowed amount after the applicable deductible has been met.
Consider these simplified examples:
| Situation | Possible patient cost |
| In-network therapist with copay | A fixed copay per visit |
| In-network therapist before deductible | Potentially a larger portion of the allowed cost |
| Out-of-network therapist with benefits | Potentially a portion reimbursed after claim processing |
| Out-of-network therapist without benefits | Potentially the full private-pay rate |
These are examples only. Your actual costs depend on your insurance plan.
How Do You Know If Your Insurance Covers Therapy?
The most reliable way to find out is to check your plan’s benefits or contact your insurance company.
Ask these questions before scheduling regular therapy:
- Does my plan cover outpatient mental health therapy?
- Are individual therapy sessions covered?
- Is my therapist in network?
- Does my plan have out-of-network mental health benefits?
- What is my mental health copay?
- What is my deductible?
- How much of my deductible have I already met?
- What is my coinsurance after the deductible?
- Do I need a referral?
- Do I need prior authorization?
- Are there visit limits or other restrictions?
- Do I need to submit claims myself if I see an out-of-network therapist?
Write down the answers.
Insurance terminology can be confusing, and having the information in front of you makes it easier to compare therapists and estimate your potential cost.
Does Insurance Cover Out-of-Network Therapy?
Sometimes.
This is one of the most important distinctions to understand when looking for a therapist.
An in-network therapist has a contractual relationship with your insurance plan.
An out-of-network therapist generally does not have that same contractual relationship with your plan.
That doesn’t automatically mean an out-of-network therapist isn’t covered.
Some insurance plans include out-of-network benefits.
Others may provide limited out-of-network coverage or none at all.
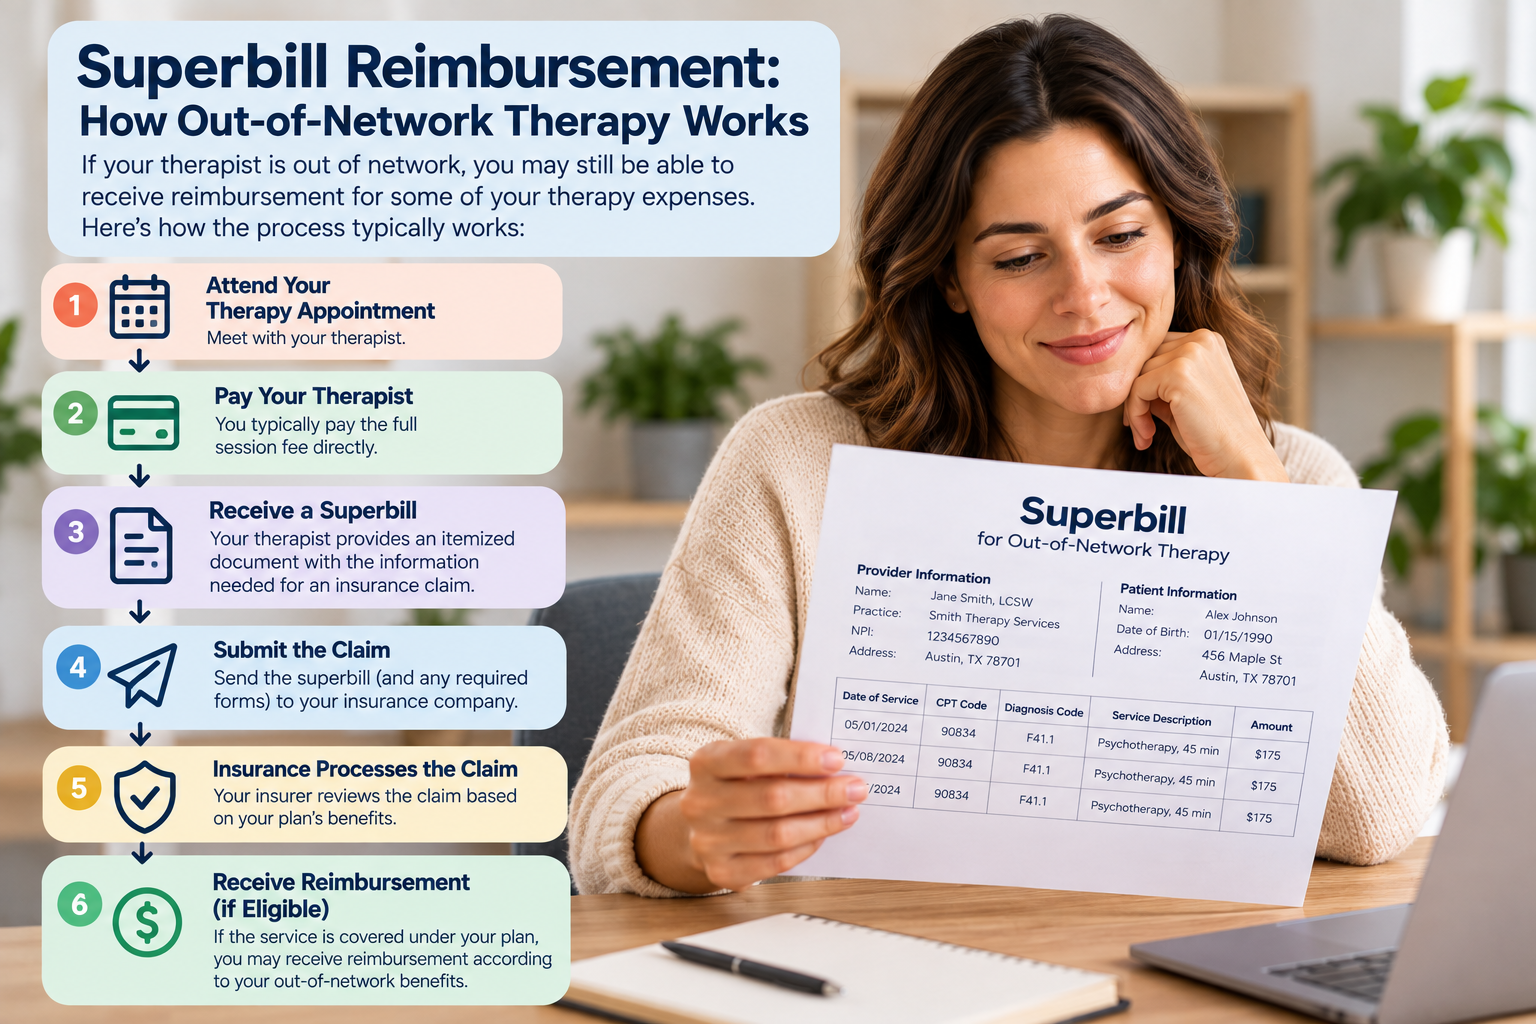
If your plan does provide out-of-network benefits, you may need to:
- Pay the therapist directly.
- Receive a superbill.
- Submit the required claim documentation.
- Wait for the insurance company to process the claim.
- Receive an explanation of benefits.
- Receive reimbursement if the claim is eligible under your plan.
Learn more in ++What Is an Out-of-Network Provider?++.
What Is Out-of-Network Therapy Reimbursement?
Out-of-network reimbursement is the process by which an insurance plan may reimburse you for eligible services from a provider who is not contracted with your plan.
The process commonly looks like this:
Therapy appointment → Pay therapist → Receive superbill → Submit claim → Insurance processes claim → EOB → Reimbursement, if eligible
The reimbursement amount isn’t necessarily based on the therapist’s full fee.
An insurer may determine an allowed amount and then apply the plan’s deductible, coinsurance, or other rules.
Example
Suppose:
- Your therapist charges $175.
- You pay $175 at the appointment.
- Your plan provides out-of-network mental health benefits.
- Your insurer determines an allowed amount of $120.
- Your applicable coinsurance is 60%.
- Your deductible has already been satisfied.
A simplified example would be:
$120 × 60% = $72 potential insurance payment
Your remaining cost would be:
$175 − $72 = $103
This is only an illustration. It is not a prediction of what an insurance company will reimburse.
For a deeper explanation, read ++Superbill Reimbursement: How Out-of-Network Therapy Works++.
What Is a Superbill?
A superbill is an itemized document that a healthcare provider may give a patient to document services provided and amounts charged or paid.
For out-of-network therapy, a superbill may contain information such as:
- Patient information
- Therapist information
- Provider NPI
- Date of service
- Service information
- Procedure code
- Diagnosis information, when applicable
- Amount charged
- Amount paid
- Provider information or signature, when applicable
The exact information required can vary by payer and claim.
A superbill is often used to support an out-of-network insurance claim, but a superbill does not guarantee reimbursement.
Your insurer determines whether the service is covered and how the claim is processed.
See ++Mental Health Superbill Template++ for a detailed look at the information that may appear on a therapy superbill.
Is a Superbill the Same as an Insurance Claim?
No.
A superbill is provider documentation.
An insurance claim is a request for the insurer to process a healthcare service under the patient’s insurance plan.
Depending on the insurer’s process, the superbill may be submitted as supporting documentation with a claim.
This distinction matters because receiving a superbill doesn’t necessarily mean that your insurance company has received a claim.
If you’re responsible for submitting the claim, you should confirm that the insurer received it.
Read ++How to Submit Therapy Claims to Insurance++.
What Is an Insurance Deductible for Therapy?
A deductible is the amount you may have to pay for covered healthcare services before your insurance plan begins paying according to its terms.
Your plan may have separate rules for:
- In-network services
- Out-of-network services
- Mental health services
- Other categories of care
For example, suppose your plan has a $1,500 out-of-network deductible.
If you have not met that deductible, an eligible therapy claim may be applied toward the deductible rather than producing an immediate reimbursement payment.
Once the applicable deductible has been satisfied, your plan may begin paying according to its coinsurance or other benefits.
Always check your plan’s specific rules.
What Is a Therapy Copay?
A copay is generally a fixed amount you pay for a covered healthcare service.
For example, your insurance plan might specify a $30 copay for certain in-network outpatient mental health visits.
But don’t assume every therapy appointment has the same copay.
Your cost may depend on:
- Provider network status
- Type of service
- Plan design
- Deductible status
- Other applicable benefits
Your insurer can tell you which cost-sharing rules apply to your plan.
What Is Coinsurance for Therapy?
Coinsurance is generally the percentage of an eligible healthcare cost that you are responsible for after applicable deductible requirements have been met.
For example, a plan could provide 70% coverage of an applicable allowed amount while the patient is responsible for the remaining 30%.
The calculation isn’t necessarily based directly on the therapist’s retail fee.
For out-of-network care especially, the insurer may determine an allowed amount before applying the plan’s cost-sharing rules.
That’s why asking an insurer only:
“What percentage of therapy does my insurance cover?”
may not give you enough information.
You also want to understand what amount the percentage is applied to.
Why Is Therapy Sometimes More Expensive With Insurance?
Having insurance doesn’t necessarily mean therapy will be cheaper in every situation.
Your cost may depend on:
- Deductible
- Copay
- Coinsurance
- Network status
- Allowed amount
- Coverage limitations
- Provider availability
An out-of-network therapist may charge $175 privately, while an in-network therapist might have a lower negotiated rate.
But an out-of-network therapist could still be financially viable if your plan provides meaningful out-of-network reimbursement.
This is why patients should compare total expected cost, not just the therapist’s advertised fee.
Why Don’t Some Therapists Take Insurance?
There are several reasons therapists may choose not to participate in insurance networks.
These can include:
- Administrative workload
- Insurance claim management
- Reimbursement rates
- Documentation requirements
- Practice model
- Provider availability
- Desire for a private-pay practice
For patients, this doesn’t necessarily mean an out-of-network therapist is unaffordable.
If your plan includes out-of-network benefits, you may be able to submit claims for eligible therapy services.
Learn more in ++Why Don’t Therapists Take Insurance?++.
What Should You Do If Your Therapist Doesn’t Accept Insurance?
Don’t automatically assume you have to pay the entire cost yourself.
First, ask your insurance company about out-of-network benefits.
Then ask the therapist:
- What is your session fee?
- Do you provide superbills?
- How frequently are superbills provided?
- What information is included?
- Do you submit claims on behalf of patients?
- What payment is due at the time of service?
If your insurance provides out-of-network benefits, ask the insurer how you should submit the therapist’s documentation.
You can then compare your expected reimbursement with the therapist’s fee.
Can You Get Insurance Reimbursement Without an In-Network Therapist?
Possibly.
An out-of-network therapist can potentially be reimbursable if your plan includes applicable out-of-network benefits and the services meet the plan’s requirements.
The typical workflow may be:
Step 1: Verify benefits
Confirm that your plan covers out-of-network mental health services.
Step 2: See your therapist
Pay according to the therapist’s payment policy.
Step 3: Get your superbill
Request documentation for the service.
Step 4: Submit your claim
Follow your insurer’s claim-submission instructions.
Step 5: Wait for processing
The insurer reviews the claim.
Step 6: Review your EOB
Check how the insurer handled the claim.
Step 7: Receive reimbursement, if eligible
The insurer pays according to your plan’s applicable terms.
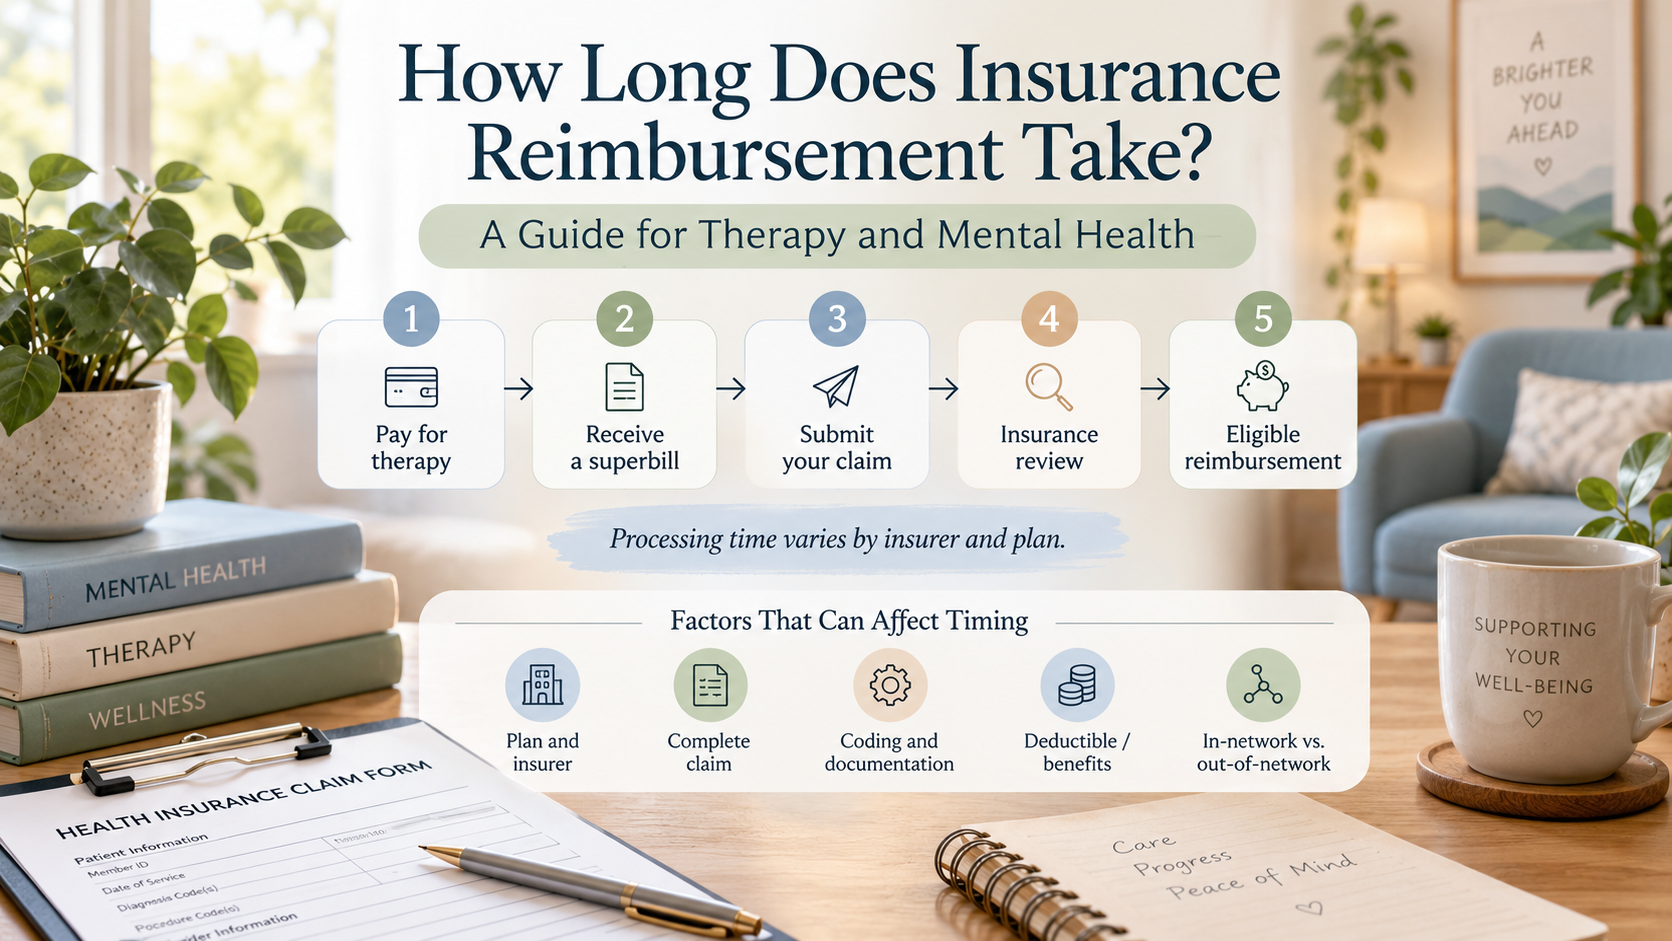
For more information, see ++How Long Does Insurance Reimbursement Take?++.
How Much Does Insurance Pay for Therapy?
There is no universal amount.
Two patients seeing therapists who charge the same fee could receive different reimbursement because they have different insurance plans.
The amount can depend on:
- Allowed amount
- Deductible
- Coinsurance
- Copay
- Network status
- Coverage
- Plan limits
- Claim requirements
For example, one patient may have a plan that covers most of an in-network session after a small copay.
Another may have an out-of-network plan where the patient pays the therapist upfront and later receives partial reimbursement.
Read ++How Much Does Insurance Pay for Therapy?++ for a more detailed explanation.
What If Your Insurance Denies Your Therapy Claim?
A denied claim isn’t necessarily the end of the process.
Start by finding out why the claim was denied.
Possible reasons can include:
- Missing information
- Incorrect information
- Eligibility problems
- Deductible requirements
- Authorization requirements
- Coverage limitations
- Provider information issues
- Filing deadlines
- Other plan-specific requirements
Review the explanation of benefits or denial notice.
Then contact your insurer if you need clarification.
If you believe the claim was incorrectly denied, ask about the insurer’s correction, reconsideration, or appeal process.
Keep copies of:
- Your superbill
- Claim form
- Submission confirmation
- EOB
- Correspondence
- Payment records
Does Mental Health Parity Require Insurance to Cover All Therapy?
No.
Mental health parity laws generally address how mental health and substance use disorder benefits are treated relative to medical/surgical benefits when those benefits are offered, but parity does not mean every therapy service is automatically covered under every insurance plan.
The details can be complicated.
For additional information, see the ++U.S. Department of Labor’s Mental Health Parity resources++.
For questions about your individual benefits, your insurance plan documents and insurer are the appropriate sources.
How Can Therapists Make Insurance Administration Easier?
Insurance administration can create substantial repetitive work for therapy practices.
A therapist may need to manage:
- Patient billing
- Payments
- Superbills
- Insurance documentation
- Claim-related information
- Reimbursement questions
- Administrative follow-up
Standardized workflows can reduce some of this manual work.
For example, billing software can help practices organize patient and billing information and automate repetitive administrative processes.
DeputyCare focuses on billing, insurance, superbills, and automation for healthcare practices.
Learn more at ++DeputyCare++.
Can AI Help With Therapy Insurance Administration?
AI and automation may help reduce repetitive administrative tasks involved in therapy billing and insurance workflows.
Potential applications include:
- Organizing billing information
- Reducing manual data entry
- Generating recurring documentation
- Identifying missing information
- Automating administrative workflows
- Tracking billing tasks
- Helping practices manage large volumes of repetitive work
However, AI does not eliminate the need for appropriate professional review.
Healthcare organizations also need to consider privacy, security, data handling, contracts, and applicable regulatory requirements when implementing AI systems.
See ++How AI Is Transforming Therapy Superbill and Insurance Workflows++.
How to Check Therapy Insurance Coverage: A Simple Checklist
Before starting therapy, use this checklist.
Insurance questions
- Does my plan cover outpatient mental health therapy?
- Is my therapist in network?
- Does my plan include out-of-network benefits?
- What is my deductible?
- How much of the deductible have I met?
- What is my copay?
- What is my coinsurance?
- Do I need authorization?
- Do I need a referral?
- Are there any applicable visit limits?
- What is the claim submission process?
Therapist questions
- What is the session fee?
- What payment is due at the appointment?
- Do you provide superbills?
- How often will I receive one?
- Do you submit insurance claims?
- What documentation will I receive?
Before submitting an out-of-network claim
- Confirm your benefits
- Get your superbill
- Keep proof of payment
- Complete any required claim form
- Submit through the insurer’s approved method
- Save your confirmation
- Track the claim
- Review your EOB
Frequently Asked Questions
Is therapy covered by insurance?
Often, yes, but coverage varies by insurance plan. Your cost depends on factors such as network status, deductible, copay, coinsurance, covered services, and other plan requirements.
Does health insurance cover therapy?
Many health insurance plans cover some mental health services, including therapy, but the specific benefits and cost-sharing rules vary by plan.
Does my health insurance cover an out-of-network therapist?
It may. Some plans provide out-of-network mental health benefits. Check your specific plan before beginning treatment.
Can I get reimbursed for therapy if my therapist doesn’t accept insurance?
Possibly. If your plan provides out-of-network benefits, you may be able to pay your therapist directly and submit the required documentation for reimbursement.
What is a superbill for therapy?
A superbill is an itemized healthcare document that may contain information needed to support an insurance claim for therapy services.
How do I submit a superbill to insurance?
Your insurer determines its claim process. You may need to submit the superbill with a claim form through an online portal, app, mail, or another approved method.
Does a superbill guarantee insurance reimbursement?
No. A superbill documents services but does not guarantee that your insurance company will reimburse you.
How much will insurance pay for therapy?
There is no universal reimbursement amount. It depends on your plan, network status, deductible, allowed amount, coinsurance, and other applicable benefits.
How long does therapy insurance reimbursement take?
There is no single timeline for every insurer or claim. Processing can depend on the insurer, submission method, completeness of the claim, and whether additional review is required.
Why don’t some therapists accept insurance?
Therapists may choose not to participate in insurance networks for reasons including administrative workload, reimbursement rates, documentation requirements, or their preferred practice model.
The Bottom Line
Therapy may be covered by health insurance, but your actual cost depends on your specific plan and therapist.
The first thing to determine is whether your therapist is in network or out of network.
If your therapist is in network, your plan may pay the provider according to the contracted arrangement, leaving you responsible for applicable cost-sharing.
If your therapist is out of network, your plan may still provide reimbursement. In that situation, you may pay the therapist directly, receive a superbill, submit a claim, and receive reimbursement according to your insurance benefits.
Before choosing a therapist, verify:
Coverage → Network status → Deductible → Copay/coinsurance → Out-of-network benefits → Claim requirements
Understanding these details upfront can make therapy costs much more predictable—and can help you decide whether an out-of-network therapist is financially workable for you.
Related DeputyCare Resources
Superbill
- ++Superbill for Therapists++
- ++Mental Health Superbill Template++
- ++How to Create a Superbill for Therapy++
- ++Superbill Reimbursement: How Out-of-Network Therapy Works++
Insurance
- ++What Is an Out-of-Network Provider?++
- ++How to Submit Therapy Claims to Insurance++
- ++How Much Does Insurance Pay for Therapy?++
- ++How Long Does Insurance Reimbursement Take?++
- ++Why Don’t Therapists Take Insurance?++