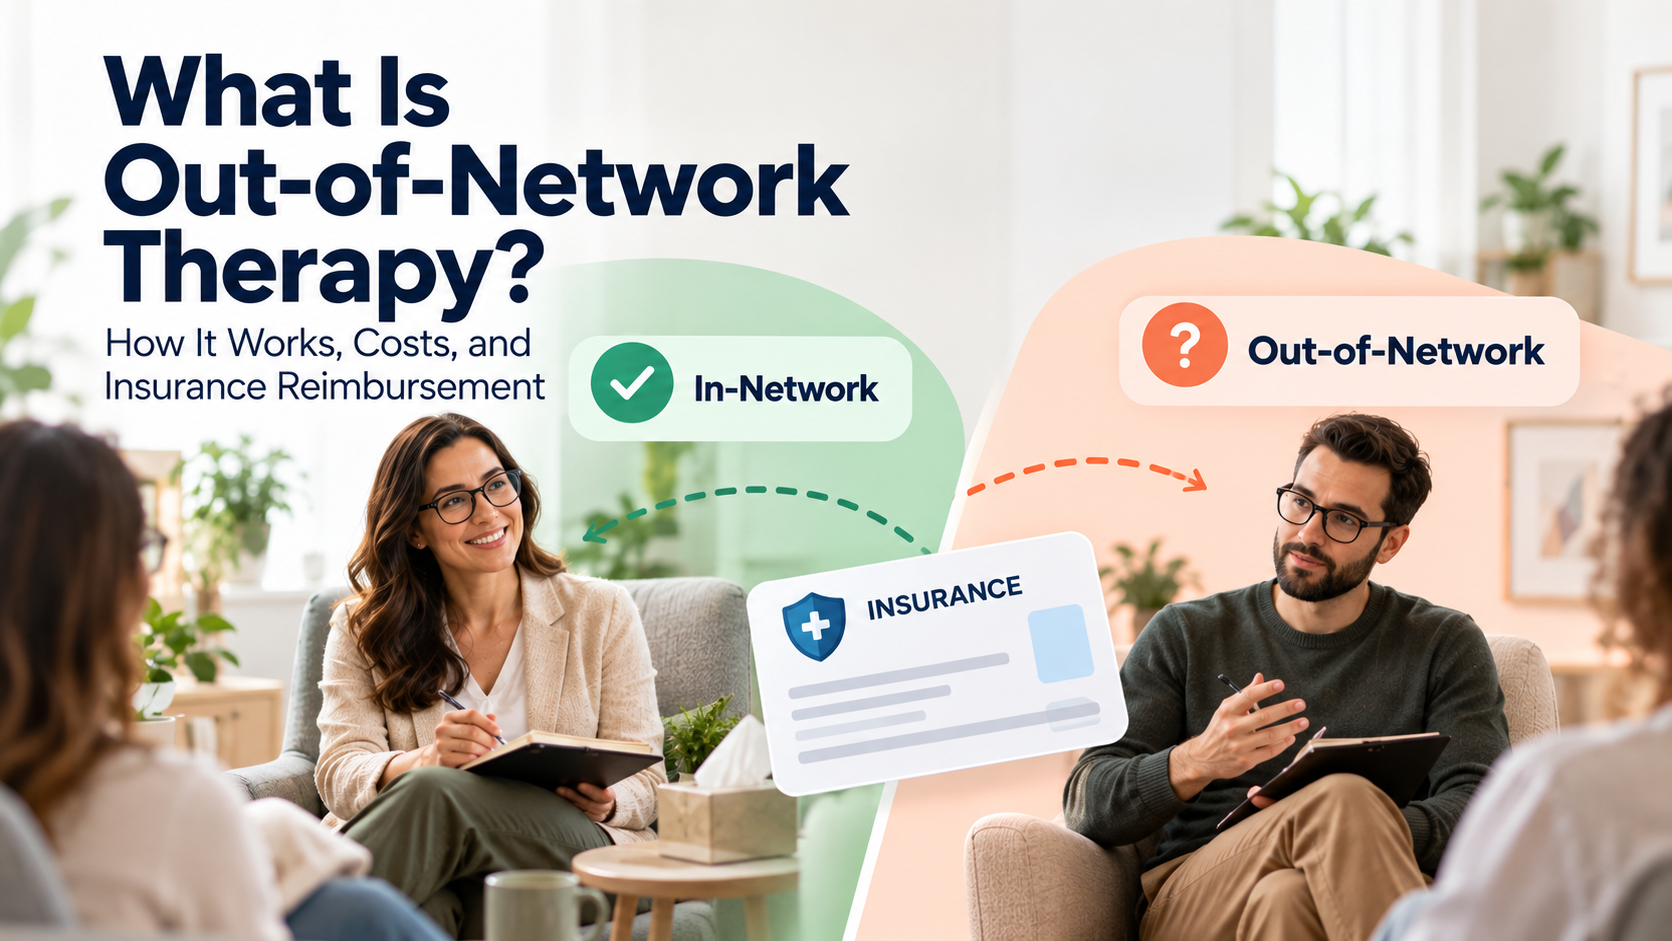
Out-of-network therapy means you receive mental health care from a therapist who does not have a contracted network relationship with your health insurance plan.
That does not necessarily mean your insurance won’t pay anything.
If your plan includes out-of-network mental health benefits, you may be able to submit eligible therapy expenses to your insurer for reimbursement. Depending on the plan, you may pay the therapist directly and use documentation such as a superbill to support your claim.
The important distinction is:
Out-of-network describes the therapist’s relationship with your insurance network. It does not automatically mean the therapy is uninsured.
Your actual coverage and reimbursement depend on your specific health plan.
How does out-of-network therapy work?
A typical out-of-network therapy arrangement works like this:
- You choose a therapist who is not in your insurance plan’s network.
- You pay the therapist according to their fee policy.
- The therapist provides documentation of the services, potentially including a superbill.
- You submit a claim to your insurance company if your plan allows out-of-network reimbursement.
- The insurer processes the claim according to your plan.
- You receive an explanation of benefits (EOB) or similar claim determination.
- If the claim is eligible, the insurer reimburses you according to the plan’s applicable rules.
The exact process varies by insurer and plan.
Some plans have substantial out-of-network benefits. Others have limited benefits or none for certain services.
That’s why checking your benefits before starting therapy can prevent unexpected costs.
What does out-of-network mean for therapy?
When a therapist is in network, they generally have a contractual relationship with an insurance network.
When a therapist is out of network, they generally don’t have that same contractual relationship with your plan.
This can affect:
- What you pay the therapist
- Whether you can submit claims yourself
- Whether the plan reimburses you
- Your deductible
- Your coinsurance
- The insurer’s allowed amount or reimbursement methodology
- Your overall out-of-pocket cost
Being out of network does not by itself determine whether therapy is covered.
Your insurance plan does.
In-network vs. out-of-network therapy
| In-network therapy | Out-of-network therapy |
| Therapist participates in the plan’s network | Therapist does not participate in the plan’s network |
| Provider may submit claims directly | Patient may need to submit claims |
| Contracted rates may apply | Out-of-network reimbursement rules may apply |
| Patient may owe a copay or coinsurance | Patient may initially pay the therapist |
| Plan-specific network benefits apply | Plan-specific out-of-network benefits apply |
These are general distinctions. Your plan documents determine the actual financial responsibility.
For a more detailed explanation of network status, see ++What Is an Out-of-Network Provider?++.
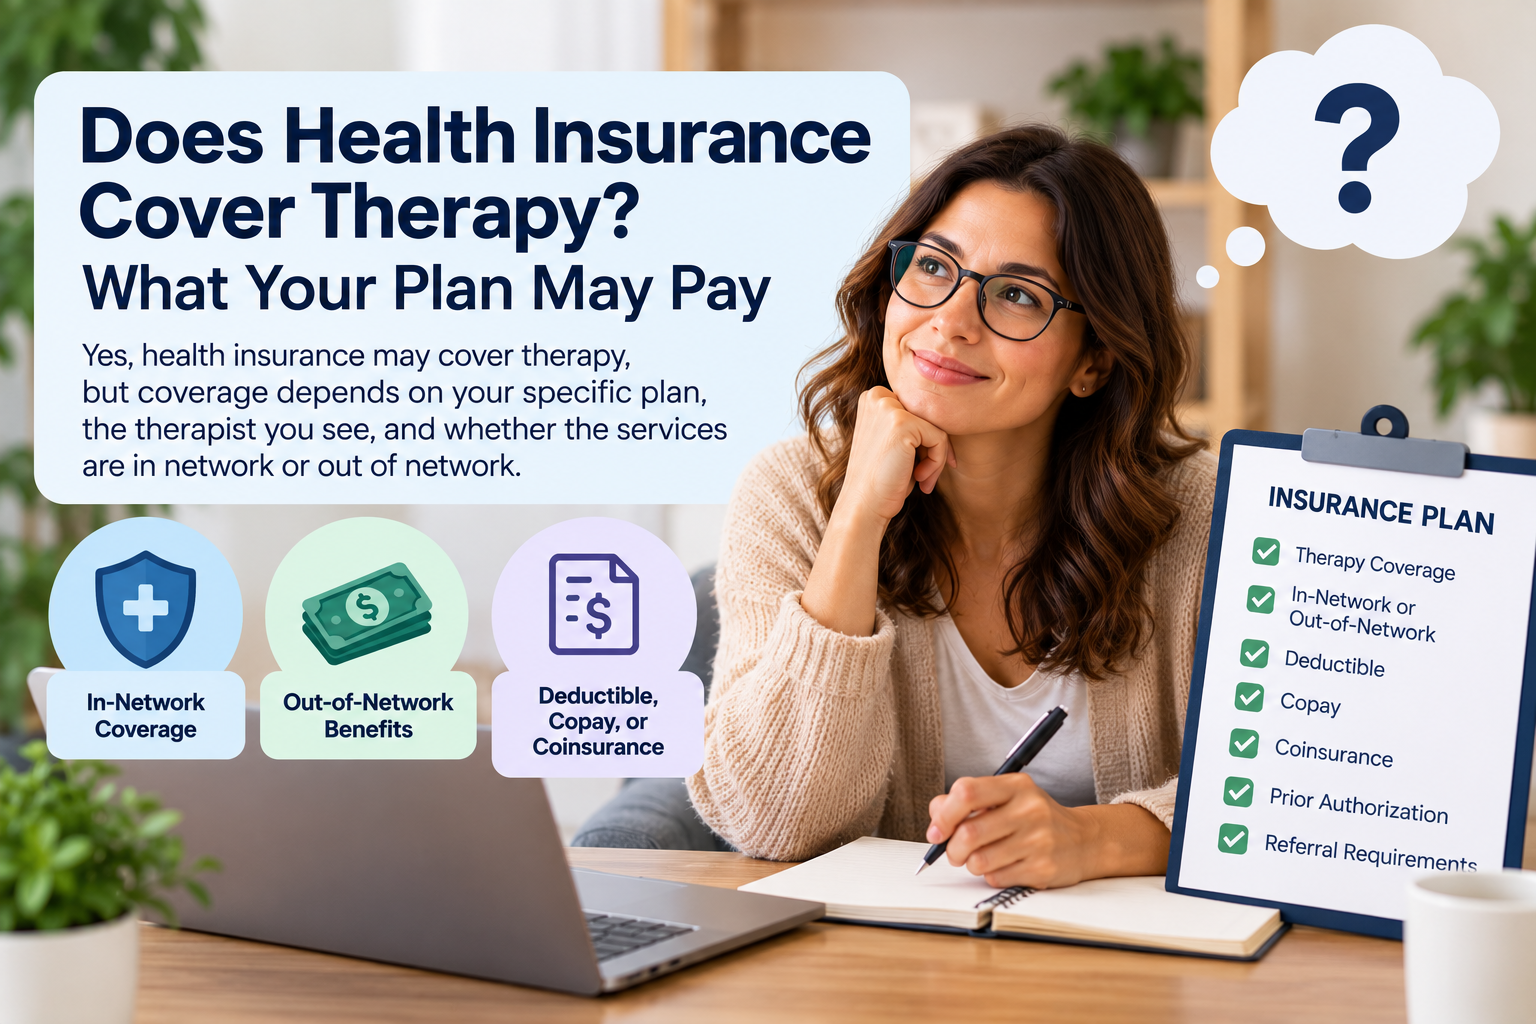
Does insurance cover out-of-network therapy?
It can, depending on your health plan.
Some health insurance plans provide benefits for eligible services from out-of-network providers. Others may offer limited out-of-network coverage or require you to pay the full cost yourself.
Before scheduling regular appointments, check:
- Whether outpatient mental health therapy is covered
- Whether out-of-network mental health benefits are included
- Your out-of-network deductible
- Your coinsurance
- Any applicable copayment
- How the plan determines reimbursement
- Whether prior authorization is required
- Whether there are claim filing deadlines
- How you submit out-of-network claims
A useful question for your insurer is:
“Does my plan provide out-of-network benefits for outpatient mental health therapy?”
You can also ask:
“If I see an out-of-network therapist, how do I submit a claim for reimbursement?”
For more information, see ++Does Health Insurance Cover Therapy?++.
How much does out-of-network therapy cost?
There is no universal price for out-of-network therapy.
The therapist sets their fee, while your insurance plan determines whether and how eligible expenses may be reimbursed.
Your effective cost can depend on:
- The therapist’s fee
- Your plan’s deductible
- Your coinsurance
- Your out-of-network benefits
- The insurer’s allowed amount
- How much you’ve already spent toward your deductible
- Whether the service is covered
- Any applicable plan limitations
Example
Suppose an out-of-network therapist charges $175 per session.
You pay the therapist $175.
Your insurance plan may determine that the applicable allowed amount is $130 and that, after any applicable deductible, the plan pays 60% of that amount.
In this simplified example:
$130 × 60% = $78
The insurer could therefore reimburse $78, subject to the actual terms of the plan.
That would leave the patient with an effective cost of $97 for the session in this simplified scenario.
This is only an illustration. Actual reimbursement can be substantially different depending on the insurance plan and claim.
For more detail, see ++How Much Does Insurance Pay for Therapy?++.
What is an out-of-network deductible?
An out-of-network deductible is the amount you may have to pay toward eligible out-of-network healthcare expenses before your plan begins paying according to its applicable reimbursement rules.
For example, imagine your plan has:
- $2,000 out-of-network deductible
- 60% coinsurance after the deductible
If you haven’t met the deductible, you may have to pay eligible expenses yourself before the plan begins contributing according to the coinsurance benefit.
But deductible structures vary.
Some plans have separate in-network and out-of-network deductibles. Some services may be treated differently. Some plans may have no out-of-network coverage at all.
Always check your specific plan.
What is out-of-network coinsurance?
Coinsurance is the percentage of an eligible healthcare expense that you may be responsible for after applicable deductible requirements are satisfied.
For example:
| Example | Amount |
| Insurer’s applicable allowed amount | $130 |
| Plan pays 60% | $78 |
| Patient responsibility | $52 |
This does not necessarily mean the patient only owes $52 to the therapist.
If the therapist’s charge is $175, the patient may still have responsibility for the difference between the therapist’s charge and the amount the insurer uses in its reimbursement calculation, depending on applicable plan rules and circumstances.
That’s one reason out-of-network therapy can be more expensive than simply looking at the coinsurance percentage.
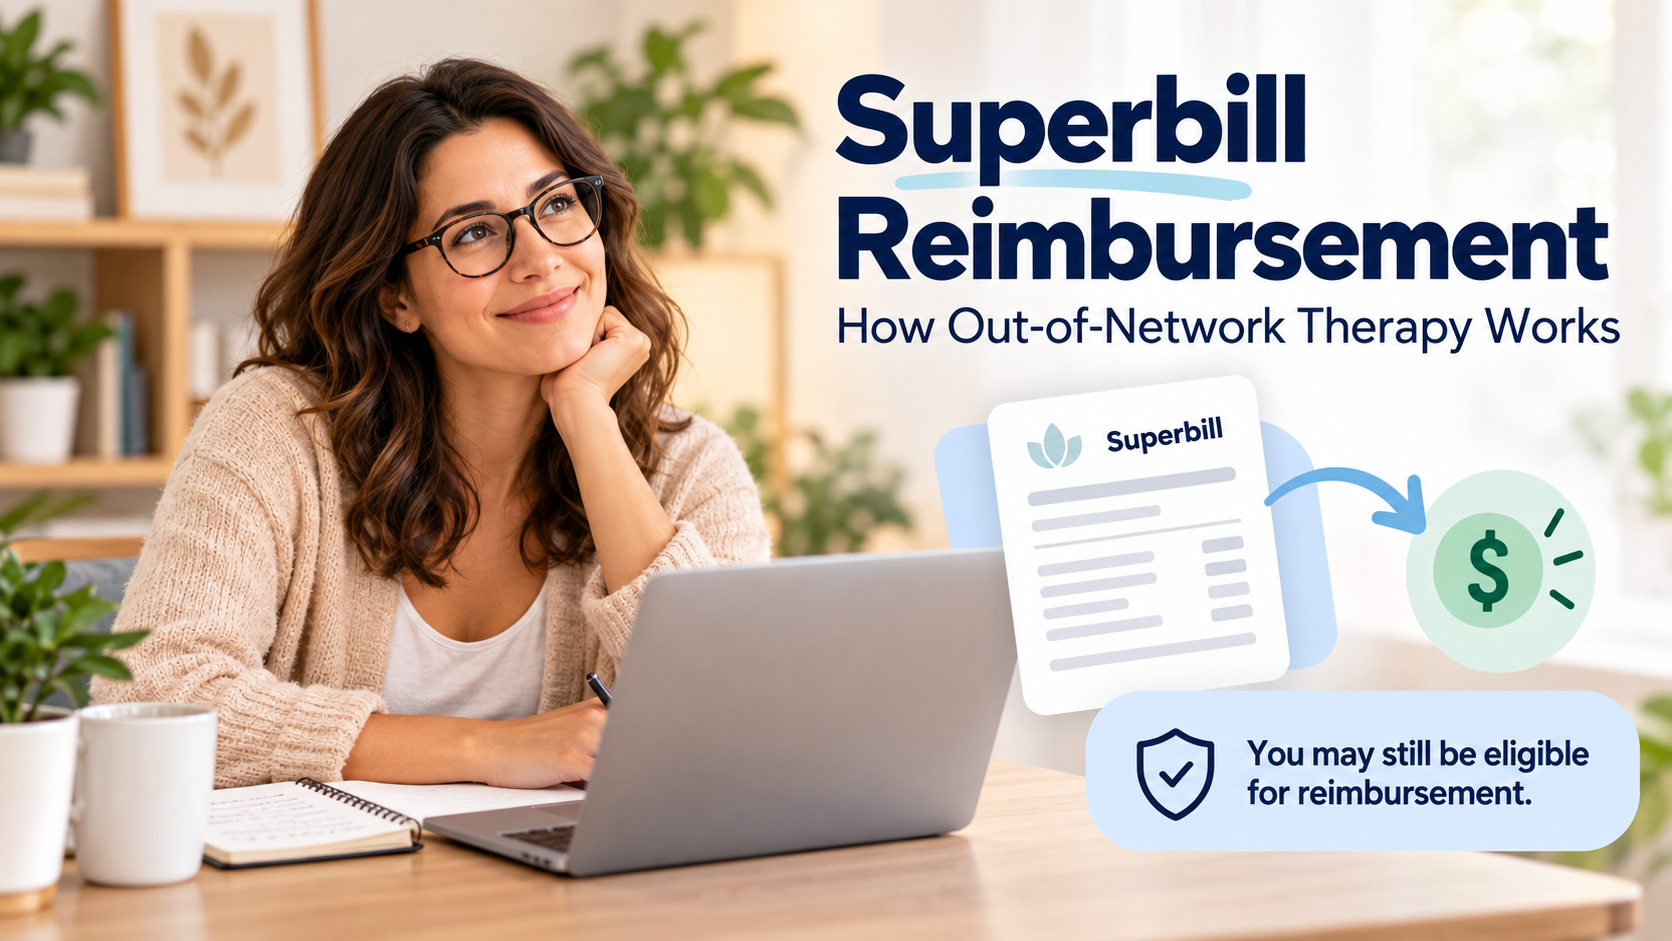
Do you need a superbill for out-of-network therapy?
Often, a superbill can be used to support an out-of-network claim.
A superbill is documentation of services provided by a healthcare professional.
For therapy, it may contain information such as:
- Therapist or practice information
- Provider identification information
- Patient information
- Date of service
- Service information
- Applicable procedure code
- Applicable diagnosis code
- Amount charged
- Amount paid
- Other information required by the payer
The insurer may require additional documentation or a member claim form.
So don’t assume that simply receiving a superbill means you have completed the claim.
For more information, read ++Superbill Reimbursement++.
How do you get reimbursed for out-of-network therapy?
The general process is:
1. Verify your benefits
Confirm that your plan provides out-of-network mental health coverage.
2. Ask about reimbursement
Ask the insurer how it calculates reimbursement for out-of-network therapy.
3. Ask about the deductible
Find out whether you have a separate out-of-network deductible and how much remains.
4. Ask about claim submission
Determine whether you need:
- A claim form
- A superbill
- A receipt
- Additional documentation
5. Pay your therapist
Follow your therapist’s payment policy.
6. Obtain documentation
Request the superbill or other documentation needed for your claim.
7. Submit the claim
Use the insurer’s current approved submission process.
8. Review the EOB
Check how the insurer processed the claim and how much it applied toward your deductible, reimbursement, or patient responsibility.
For a detailed walkthrough, see ++How to Submit Therapy Claims to Insurance++.
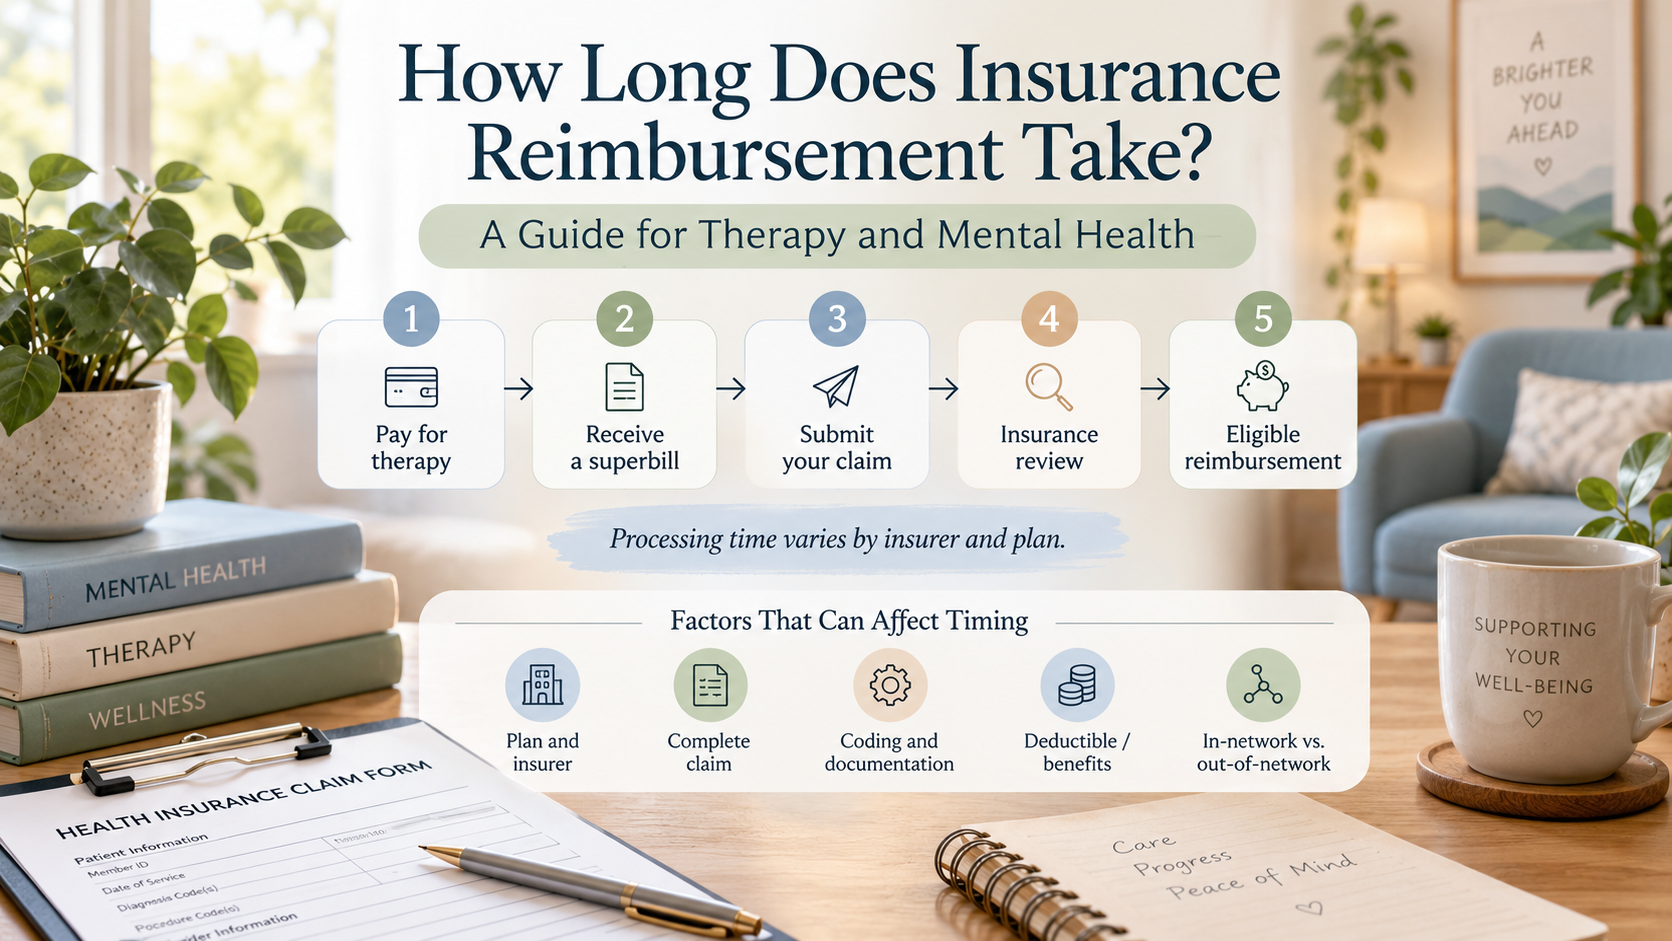
How long does out-of-network therapy reimbursement take?
There is no universal reimbursement timeline.
Processing can depend on:
- The insurance company
- Submission method
- Claim completeness
- Whether additional information is requested
- Eligibility verification
- Manual review
- The insurer’s processing workflow
Keep your claim confirmation and documentation so you can follow up if necessary.
See ++How Long Does Insurance Reimbursement Take?++ for a more detailed explanation.
Why would someone choose an out-of-network therapist?
Cost isn’t the only factor when choosing a therapist.
Someone might choose an out-of-network therapist because they:
- Have a particular clinical specialty
- Have experience with a specific condition or population
- Offer a treatment approach the patient prefers
- Have availability when in-network therapists do not
- Are a strong personal or therapeutic fit
- Offer appointment times that work better
- Provide a location or telehealth arrangement that is more convenient
For some patients, the additional out-of-pocket cost may be worthwhile.
For others, in-network care may be financially preferable.
The right choice depends on the patient’s needs, preferences, availability, and insurance benefits.
Why are some therapists out of network?
Therapists may choose not to participate in insurance networks for a variety of practice and administrative reasons.
Insurance participation can involve:
- Credentialing
- Contracting
- Claims administration
- Documentation requirements
- Payer-specific processes
- Payment and reimbursement considerations
- Administrative workload
Some therapists therefore operate partially or entirely outside insurance networks.
That doesn’t necessarily mean they cannot provide documentation for patients who want to seek out-of-network reimbursement.
Read more: ++Why Don’t Therapists Take Insurance?++.
Is out-of-network therapy worth it?
There isn’t one answer for everyone.
Consider the tradeoff between:
Potential advantages
- Greater therapist choice
- Access to specific expertise
- Potentially shorter wait times
- More flexibility in choosing a provider
- Ability to continue with a preferred therapist even when they’re not in network
Potential disadvantages
- Higher upfront cost
- Larger deductible
- More complicated reimbursement
- Potentially lower insurance reimbursement
- More paperwork for the patient
- Risk of unexpected costs if benefits aren’t verified
A useful way to evaluate the decision is to calculate your expected net cost per session, rather than looking only at the therapist’s advertised fee.
How to calculate your potential out-of-network therapy cost
Before committing to regular sessions, ask your insurer for the information needed to estimate your costs.
You may want to know:
- What is my out-of-network deductible?
- How much of it have I already met?
- What is my out-of-network coinsurance?
- How does my plan determine the allowed or reimbursable amount?
- Is there a limit on covered therapy visits?
- Does therapy require authorization?
- Are there any exclusions or limitations?
- What documentation is required?
- Where do I submit an out-of-network claim?
- What is the filing deadline?
Then compare the information with the therapist’s fee.
Simple calculation
If:
Therapist fee − expected insurance reimbursement = estimated net cost
you can compare that number with the cost of available in-network options.
Because reimbursement is plan-specific, treat the result as an estimate rather than a guarantee.
What if there are no in-network therapists available?
If you can’t find an appropriate in-network therapist, don’t automatically assume that you must pay the full out-of-network rate.
Contact your insurer and explain your situation.
Ask:
“I can’t find an available in-network mental health provider who meets my needs. What options does my plan provide?”
Depending on the plan and circumstances, the insurer may have procedures for situations where an appropriate in-network provider isn’t reasonably available.
Document:
- Providers you contacted
- Dates you contacted them
- Whether they were accepting new patients
- Appointment availability
- Any information provided by the insurer
Don’t assume that a special exception or different reimbursement arrangement applies without confirming it with your insurer.
What if the insurance company says my therapist is in network when the therapist says they aren’t?
Network directories and provider information can sometimes be confusing.
If there is conflicting information:
- Contact the insurer.
- Ask for the therapist’s network status for your specific plan.
- Ask the therapist to confirm the information they have.
- Save written or reference information when available.
- Ask how the claim would be handled if the information is incorrect.
Don’t rely solely on a generic provider directory if the financial consequences are significant.
For more on verifying your therapist’s status, read ++Is My Therapist In or Out of Network?++.
Out-of-network therapy and superbills: what therapists need to know
For therapists, out-of-network care often creates an administrative workflow around documentation.
A practice may need to:
- Maintain accurate patient information
- Record dates of service
- Maintain accurate billing information
- Generate superbills
- Track payments
- Respond to patient documentation requests
- Maintain appropriate records
A standardized billing workflow can reduce repetitive administrative work.
Software can help practices organize patient, session, payment, and billing information so documentation is easier to generate consistently.
For practices exploring automation, see ++Mental Health Billing Software++.
Can software automate out-of-network therapy billing?
Administrative software can help with parts of the workflow, including:
- Patient information management
- Session tracking
- Payment records
- Superbill generation
- Billing workflows
- Administrative reminders
- Documentation organization
Automation can reduce manual data entry, but practices still need to verify information and follow applicable payer, professional, privacy, and recordkeeping requirements.
For a broader look at automation, see ++How AI Is Transforming Therapy Superbill and Insurance Workflows++.
Frequently Asked Questions About Out-of-Network Therapy
What is out-of-network therapy?
Out-of-network therapy is mental health care provided by a therapist who does not participate in your health insurance plan’s provider network.
Does out-of-network therapy mean insurance won’t pay?
No. Some health plans provide out-of-network benefits for eligible mental health services. Others provide limited benefits or no out-of-network coverage. Check your specific plan.
Is out-of-network therapy more expensive?
It can be, but the actual cost depends on the therapist’s fee and your insurance benefits. Deductibles, coinsurance, allowed amounts, and reimbursement rules can all affect what you ultimately pay.
Can you get reimbursed for out-of-network therapy?
Potentially. If your plan provides applicable out-of-network benefits, you may be able to submit eligible therapy expenses for reimbursement.
Do I need a superbill for out-of-network therapy?
A superbill can be used to document services for an out-of-network claim, but insurers may have additional requirements. Check your insurer’s current submission instructions.
How do I know if my therapist is out of network?
Ask your therapist and your insurance company. For the most reliable answer, confirm the therapist’s network status for your specific insurance plan rather than relying only on a generic provider directory.
Why don’t some therapists take insurance?
Therapists may choose not to participate in insurance networks because of contracting, credentialing, administrative, reimbursement, or practice-model considerations.
Can out-of-network therapy count toward my deductible?
It may, depending on your insurance plan and the applicable benefit rules. Check whether your plan has a separate out-of-network deductible and how eligible services are applied to it.
What happens if my out-of-network therapy claim is denied?
Review the denial information or EOB, determine why the claim was denied, and contact your insurer if you need clarification. If appropriate, correct and resubmit the claim or follow the plan’s appeal process.
Is out-of-network therapy the same as self-pay therapy?
Not necessarily.
Self-pay means you pay for the service yourself without relying on insurance payment.
An out-of-network therapist may still be eligible for reimbursement under a plan that provides out-of-network benefits.
Out-of-Network Therapy: Key Takeaways
Out-of-network therapy simply means that your therapist does not participate in your insurance plan’s network.
It doesn’t automatically mean that you have to pay the entire cost yourself.
The most important questions are:
- Does your plan cover out-of-network therapy?
- What is your out-of-network deductible?
- What coinsurance applies?
- How does the plan determine reimbursement?
- Does the insurer require a superbill?
- How do you submit the claim?
- What is the filing deadline?
If your plan provides out-of-network benefits, a superbill may help you request reimbursement for eligible therapy services.
For patients, the best way to avoid surprises is to verify benefits before beginning treatment and understand the difference between the therapist’s fee and the insurer’s reimbursement calculation.
For therapists, consistent superbill and billing workflows can make out-of-network administration easier to manage.
Related DeputyCare resources
- ++What Is an Out-of-Network Provider?++
- ++Is My Therapist In or Out of Network?++
- ++Superbill Reimbursement++
- ++Superbill for Therapists++
- ++Mental Health Superbill Template++
- ++Does Health Insurance Cover Therapy?++
- ++How to Submit Therapy Claims to Insurance++
- ++How Much Does Insurance Pay for Therapy?++
- ++How Long Does Insurance Reimbursement Take?++
- ++Why Don’t Therapists Take Insurance?++